Author: David Klemt

by David Klemt David Klemt No Comments

Stewardship Protects Gravity

Guests notice failures immediately.

They notice long wait times, dirty tables, empty shelves, missed details, and inconsistent service. They notice when something breaks, when standards slip, or when expectations go unmet.

What they rarely notice, however, is how much effort was required to prevent those failures from occurring in the first place.

A perfectly timed interaction feels natural. A spotless dining room appears effortless. A fully stocked bar, a well-maintained restroom, and a calm response to an unexpected problem are expected. A seamless shift change rarely attracts attention.

Yet each of these is the result of planning, preparation, communication, and discipline. What guests don’t see are the countless decisions made long before their arrival.
by David Klemt

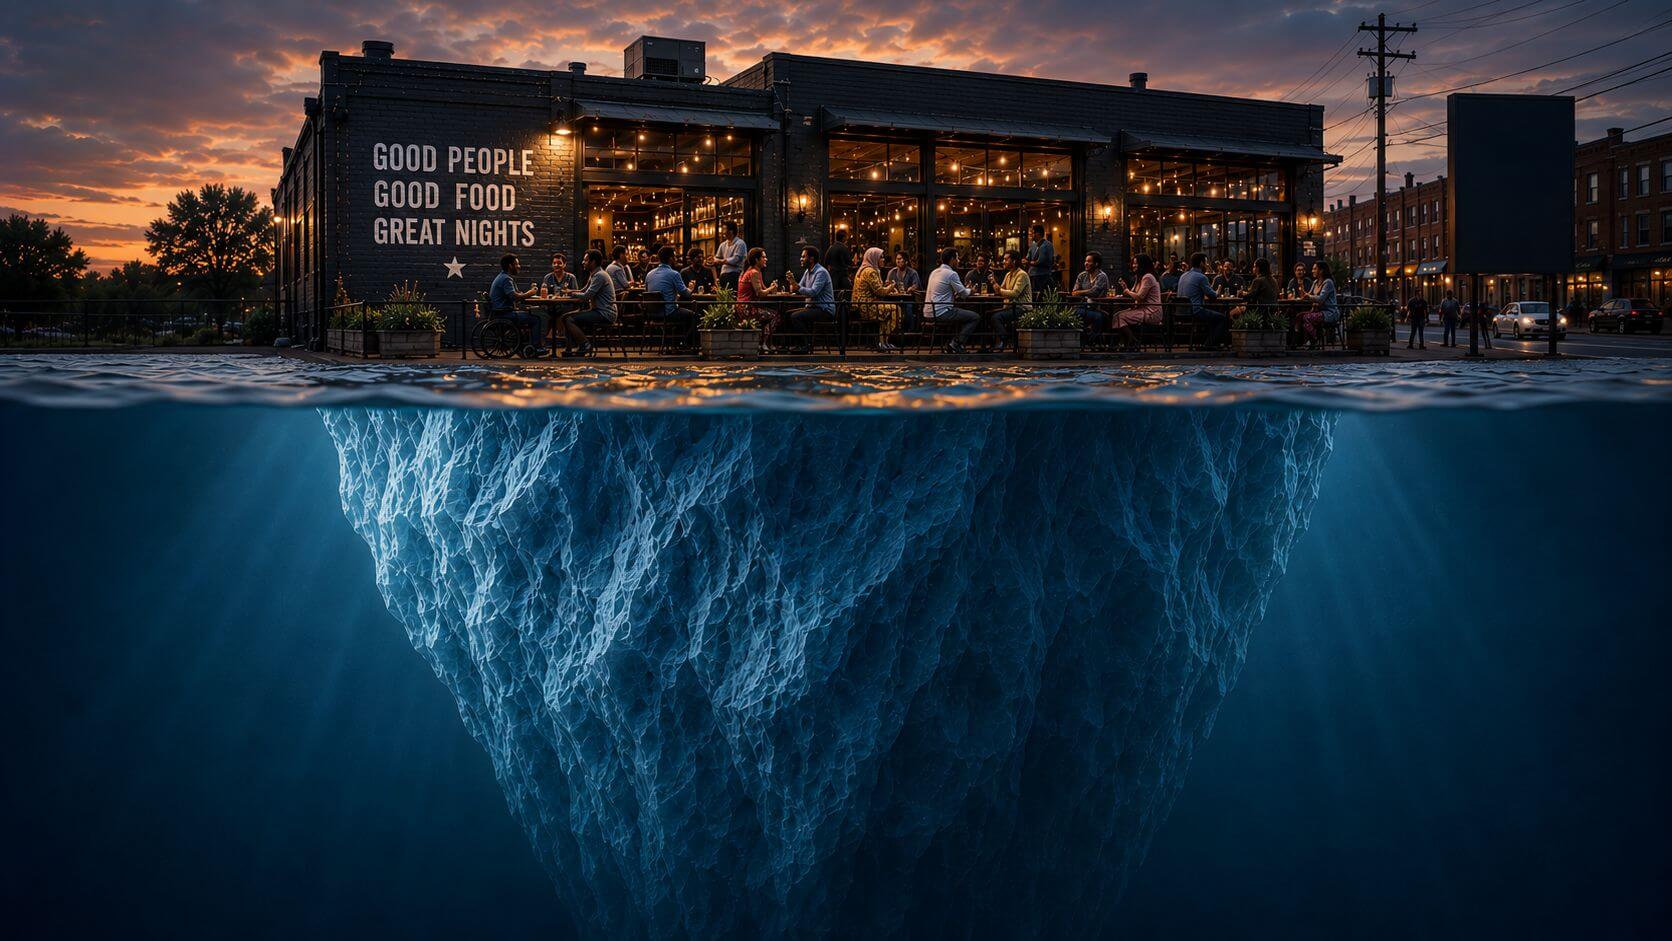
AI-generated image of a restaurant resting atop an iceberg visible only when viewed from underneath the waterline

AI-generated image

This creates one of hospitality’s most important paradoxes: the better an operation becomes, the less visible its effort appears.

The Invisible Work Behind Excellence

Guests experience outcomes rather than processes. They see the performance, not the rehearsal. Guests experience the result, not the preparation, and enjoy consistency without witnessing the systems required to create it.

The irony is that many of the most important details that contribute to the guest experience are only noticed when one or more fail.

Nobody compliments a venue because preventive maintenance worked exactly as intended. Few guests are aware of inventory accuracy and optimization, labor planning and scheduling discipline, coaching conversations, or operational audits.

And yet if an operator were to remove one of those crucial elements the guest experience would begin deteriorating almost immediately.

Excellence often looks effortless from the outside because someone has worked relentlessly to make it feel that way. That invisible effort isn’t an accident, it’s a choice.

Increasingly, it’s a competitive advantage.

The Stewardship Advantage

Today’s hospitality industry has become remarkably good at manufacturing visibility. After all, operators have been able to purchase attention more easily than they ever have before.

Operators can create promotions, launch campaigns, buy advertising, generate content, partner with influencers, and produce spectacle almost entirely from their phone.

Yet none of those activities guarantee retention. None guarantee trust. None guarantee reputation, nor do they guarantee excellence. In fact, as attention becomes easier to generate, stewardship becomes more important because guests encounter reality eventually.

The marketing ends, the promotion expires, and what’s left? The guest experiences the operation itself. When that moment arrives, stewardship determines whether perception and reality align.

The Difference Between Hospitality and Stewardship

Hospitality and stewardship are related, but they’re not the same thing. Hospitality is visible, whereas stewardship is often invisible. Hospitality happens in moments, while stewardship happens continuously. Hospitality creates memories, but stewardship creates the conditions that make those memories repeatable.

Most operators enter the industry because they care about hospitality. They enjoy welcoming guests, creating and delivering memorable experiences, and building environments people enjoy returning to. However, sustaining those experiences requires something more.

It requires stewardship. It requires maintaining standards when nobody is watching. Stewardship is investing before problems emerge, documenting before knowledge disappears, coaching before performance declines, and protecting culture before it drifts.

Danny Meyer famously wrote that hospitality is present when something happens for you and absent when something happens to you. The distinction is useful because it reminds us that hospitality is, ultimately, experienced by guests. Stewardship, however, exists largely outside their view.

Many operators want the benefits of excellence without accepting the responsibility of stewardship. They want consistency without accountability, loyalty without standards, reputation without maintenance, and influence without discipline. The market rarely rewards that approach for long.

Every successful venue eventually encounters friction: teams change, costs increase, competitors emerge, equipment ages, guest expectations evolve. Hospitality alone can’t overcome these pressures.

Stewardship is what allows a business to adapt without abandoning its standards. It protects consistency long enough for trust to develop, loyalty to form, and reputation to compound.

Stewardship isn’t glamorous. It isn’t sexy. It rarely generates headlines. What it is, however, is the difference between venues that create momentum and venues that spend years chasing it.

Excellence Can’t Be Self-Assigned

Many operators misunderstand excellence because they treat it as though it’s an internal achievement. The assumption is that excellence is something they can declare.

It isn’t.

A venue can decide to improve. It can invest in standards to tighten operations and pursue excellence. But excellence itself is a social judgment. It’s bestowed externally.

Guests decide whether excellence exists. Employees decide whether excellence exists. Peers decide. Communities decide. Markets decide.

An operator can claim excellence on a website. They can print it on menus, and place it in mission statements and marketing materials. None of those declarations matter. The market ultimately decides whether excellence exists.

This is why stewardship often goes unnoticed. Guests rarely see the standards meeting, the difficult coaching conversation, the equipment inspection, the scheduling adjustment, or the operational review. They simply experience the result. None of that work is performed for recognition. It’s performed because excellence depends on it.

Nor is excellence the outcome of a single initiative, program, or operational improvement. Earning the right to be considered excellent requires a commitment to continue doing the work required to deserve that recognition. Endlessly, tirelessly, and relentlessly. Standards and systems are never “done.” They’re living, breathing entities, and they evolve. If they’re not monitored, analyzed, discussed, and updated regularly, they drift.

Venues that drift eventually discover that excellence, like gravity, weakens the moment operators stop protecting it.
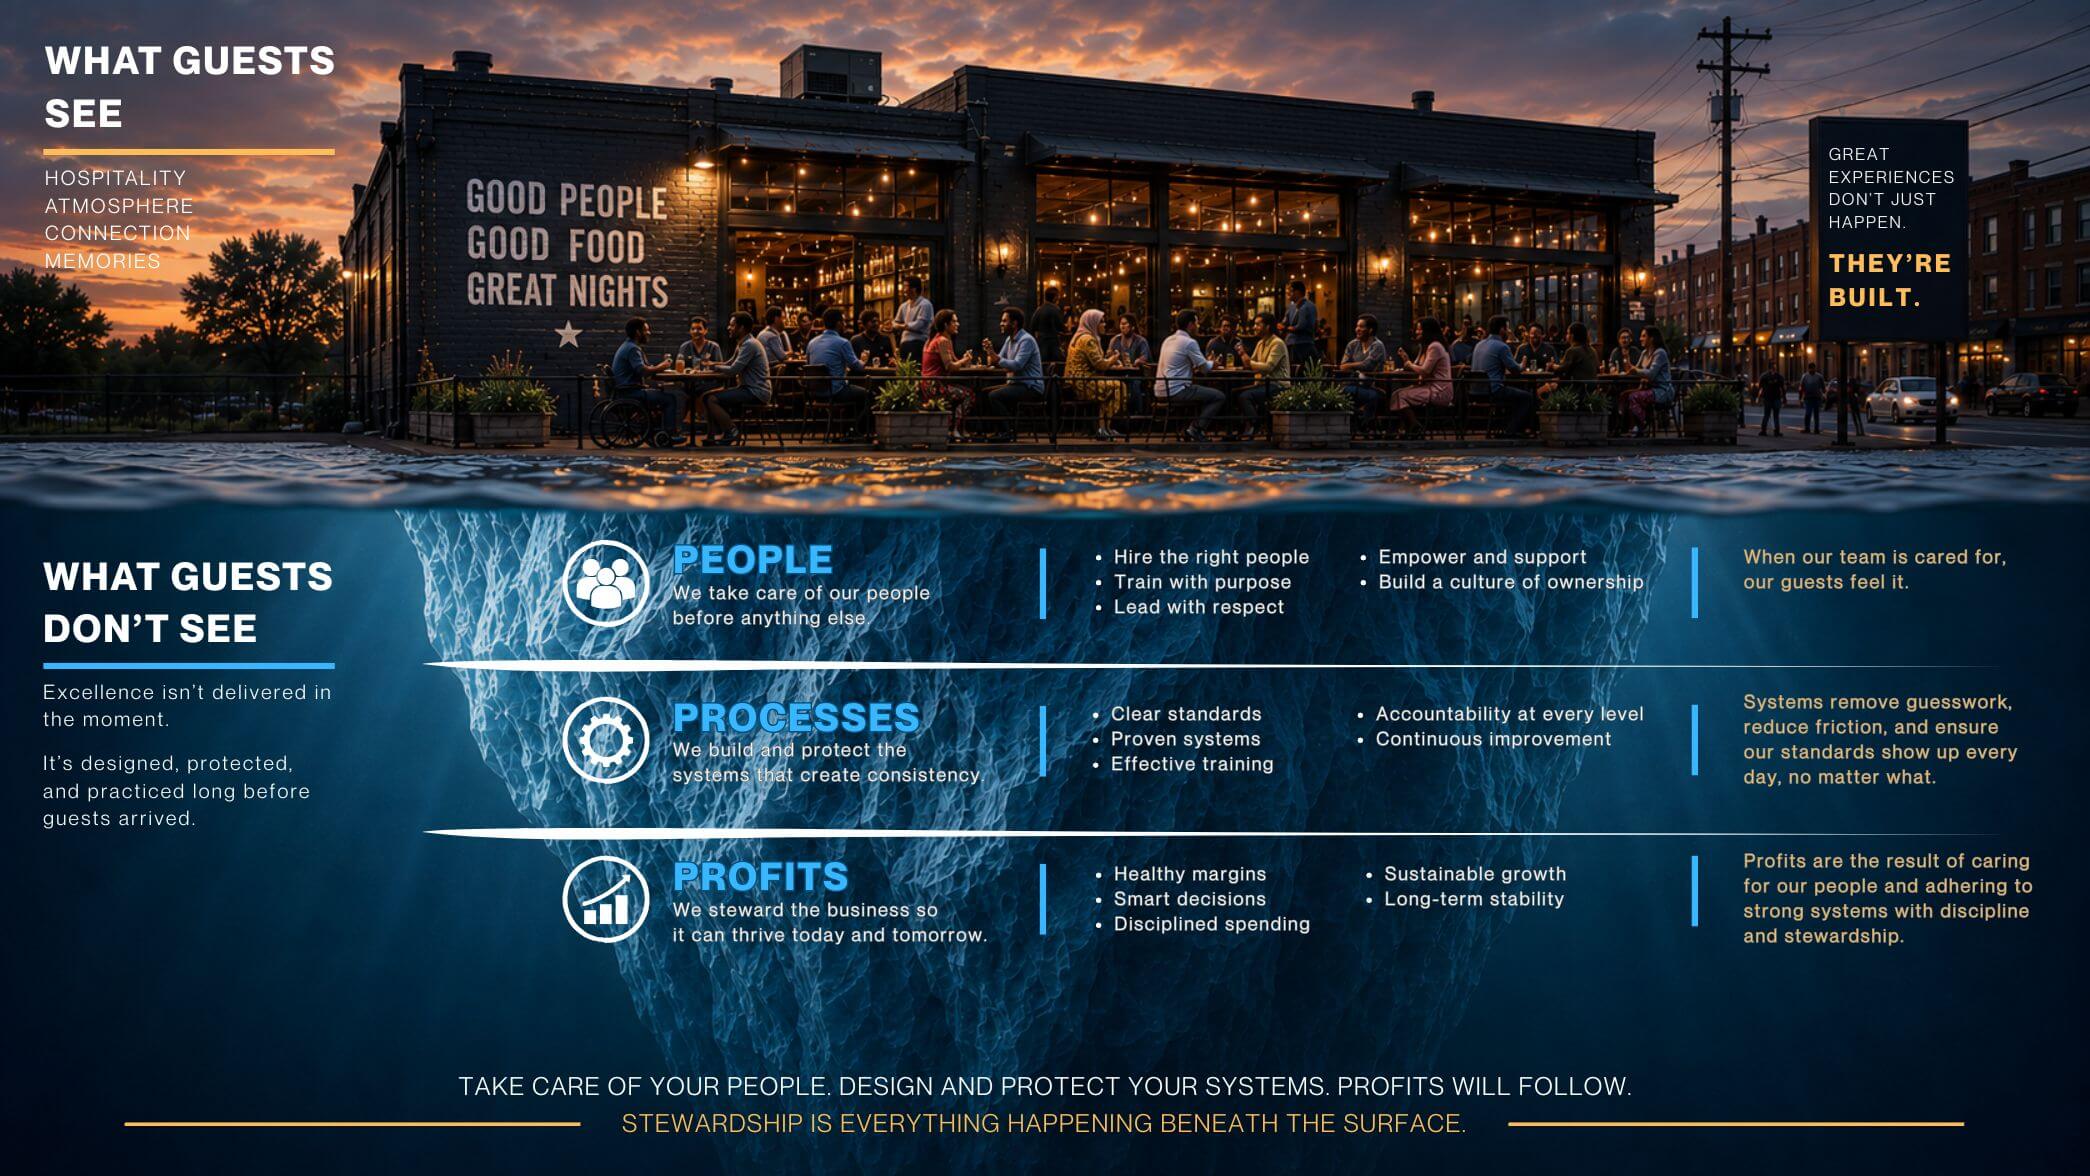
Iceberg illustration showing a busy hospitality venue above the waterline and the hidden people, systems, and operational disciplines beneath the surface that create consistent guest experiences.

Excellence Is Built in Places Guests Never See

Many operators assume excellence is created at the point of service. In reality, excellence is often built long before guests arrive.

It’s built through hiring decisions, training systems, maintenance standards, accountability structures, leadership discipline, cultural expectations, and operational consistency. By the time a guest experiences excellence, most of the important work has already been done. The interactions, vibe, and atmosphere they experience are simply the visible result of countless invisible decisions.

This is why excellence can’t be reduced to service style, guest interactions, or isolated moments of performance; excellence is a system outcome.

It emerges when standards are protected consistently enough to become reliable. When leadership continues investing in details others overlook. Excellence develops when stewardship becomes embedded within the culture rather than delegated to a few individuals.

Over time, these invisible decisions create visible results: guests return more often, teams perform more consistently, trust grows, reputation strengthens, and influence expands. Eventually, what began as operational discipline becomes something larger. It becomes gravity.

Cool attracts. Good retains. Excellence multiplies. Stewardship protects all three. Without stewardship, cool eventually becomes noise. Without stewardship, good becomes inconsistent. Without stewardship, excellence becomes a claim rather than a reality.

The brands that appear effortless are often carrying the greatest operational weight. Guests experience hospitality. Stewardship is everything happening beneath the surface to ensure that experience remains possible tomorrow, next month, and years from now.

The strongest hospitality brands aren’t built on moments alone. They’re built on the often-unseen commitment to protect standards, preserve culture, and maintain excellence long after the excitement of opening day has faded. That’s the hidden work behind hospitality excellence.

And that work is never finished.

Related Reading

Sign up for the KRG Hospitality Pre-Open Sequence emails

by David Klemt David Klemt No Comments

How to Know if Your Venue Has Gravity

The signals, behaviors, and patterns that reveal whether guests are truly connected to a hospitality brand or simply passing through it.

Most hospitality operators can feel when something is off long before they fully understand why. Traffic becomes inconsistent, marketing feels less effective, new guests arrive but fewer return. Teams work harder for weaker results. Momentum starts feeling temporary instead of stable.

Most operators initially interpret these problems tactically: marketing, pricing, promotions, staffing, programming. But the deeper issue is often harder to measure because it appears behaviorally before it appears analytically.

It’s gravity.

Gravity reveals itself through patterns. Guests behave differently around venues that create genuine pull, and teams behave differently inside them. Even the business itself operates differently over time.

by David Klemt

An AI-generated image of people converging on a neighborhood restaurant, bar, or brewpub because it has achieved gravity and become a part of their routine

AI-generated image

Most venues can generate attention for a period of time. Far fewer create the kind of pull that keeps guests returning without constant persuasion.

The Signals of Gravity

Gravity rarely announces itself dramatically. Most of the time, it appears quietly through consistency, behavior, and emotional attachment.

The strongest hospitality brands often share a few recognizable patterns.

Guests Return Naturally

The clearest sign of gravity is return behavior that doesn’t require constant prompting.

Venues without gravity depend heavily on stimulation: another campaign, another event, another push to maintain momentum. Traffic becomes difficult to stabilize because the business needs to reacquire attention constantly.

Venues with gravity operate differently. Guests return because the experience has become emotionally reliable. The venue fits naturally into routines, habits, social patterns, and decision making. At some point, guests stop actively evaluating where to go and simply return to the places they already trust.

That’s when pull begins forming.

Guests Bring Other People

Gravity expands socially. Guests who feel connected to a venue rarely keep it to themselves. They bring friends, coworkers, dates, family members, and out-of-town visitors. Recommendations happen naturally because the venue has become part of the guest’s identity and social life.

This behavior matters more than many operators realize.

People protect places they identify with emotionally. They advocate for them differently. They talk about them differently. They become emotionally invested in the experience surviving.

That kind of advocacy can’t be manufactured through advertising alone. Operators can purchase visibility; they can’t purchase genuine emotional ownership.

The Venue Becomes Easy to Describe

Strong hospitality brands create clarity. When guests describe the venue, the descriptions often sound remarkably similar. The experience feels defined enough that people understand instinctively what the place is, who it’s for, and what kind of experience to expect.

Weak gravity usually creates the opposite effect: descriptions become inconsistent, expectations vary widely between guests, and the venue starts feeling uncertain even when individual parts of the experience function adequately on their own.

Clarity creates confidence, and confidence reduces friction. Over time, that consistency becomes gravitational.

Standards Hold Under Pressure

Many hospitality businesses operate well when conditions are easy. Gravity becomes more visible under pressure.

Busy nights, staffing shortages, operational stress, unexpected volume, difficult guests… These moments reveal whether structure is protecting the experience or merely holding the business together temporarily. Guests may not see every operational issue directly, but they feel instability quickly. They notice changes in energy, inconsistency in execution, slower recovery, weaker communication, or shifts in hospitality standards.

Strong structural gravity protects the experience even when pressure increases. That protection matters because guests return to reliability, not perfection.

Marketing Feels Different

Venues with gravity still market themselves. However, the role of marketing changes. Instead of constantly compensating for weak retention, marketing amplifies an experience guests already trust.

Strong marketing amplifies gravity, weak gravity forces marketing to compensate for its absence. Campaigns perform better because the underlying business already has emotional momentum supporting it.

Without gravity, marketing becomes heavier and more expensive over time. Attention may still appear temporarily, but attention alone rarely creates loyalty. Visibility without alignment often creates noise faster than retention.

And noise is expensive.

When Gravity Weakens

Gravity can exist and still erode. One of the most dangerous assumptions in hospitality is believing strong traffic automatically means strong gravity. Some venues maintain visibility long after emotional connection, operational consistency, or guest trust has started weakening underneath the surface.

That delay creates false confidence. Guests rarely announce when gravity is fading. They simply return less frequently, make fewer recommendations, and their emotional attachment weakens quietly until the venue disappears slowly from their routine.

Most hospitality decline begins this way: gradually, then suddenly.

A Few Questions Worth Asking

Operators don’t need complicated analytics to begin recognizing whether gravity exists.

A few honest questions often reveal more than dashboards do:

  • Are guests returning naturally, or only after being prompted?
  • Do guests bring new people into the venue consistently?
  • Would guests describe the experience similarly?
  • Do standards survive operational pressure?
  • Does marketing amplify momentum or constantly compensate for weak retention?
  • Would guests genuinely miss this venue if it disappeared?

Most operators already know the answers instinctively. What they often lack is the framework to interpret what those answers mean.

The Difference

Some venues generate transactions. Others become part of people’s routines, relationships, memories, and identities. That’s the difference gravity creates.

When identity, social connection, and operational structure reinforce each other consistently over time, guests stop merely visiting the business. When gravity forms, the venue becomes part of their lives. That kind of connection is difficult to replace because it was never built transactionally in the first place.

Everything else is noise. And noise is expensive.

Related Reading

Sign up for the KRG Hospitality Pre-Open Sequence emails

by David Klemt David Klemt No Comments

The Four Forces of Gravity in Hospitality

How brand, social, and structural forces align hospitality systems to generate gravity and create venues guests return to again and again.

In hospitality, some places constantly chase guests while others pull them in. The difference isn’t marketing budgets, influencer campaigns, or the latest technology platform.

It’s gravity.

Gravity is the force that draws guests back to a venue without constant persuasion. It’s what happens when a restaurant, bar, or café becomes part of a person’s routine, conversations, and memories. Venues without gravity operate differently. They constantly need another promotion, another campaign, another push to maintain momentum. Traffic becomes unpredictable. Marketing shifts from amplification to compensation. Over time, that dependency becomes expensive, operationally exhausting, and increasingly difficult to sustain.

Gravity changes that equation. It creates return behavior strong enough to reduce the constant pressure of reacquiring attention.

However, gravity doesn’t appear accidentally. It forms when several underlying forces align inside a hospitality business. Over time, those forces create pull. If they’re allowed to weaken, gravity disappears.

by David Klemt

Symmetrical fields of force stabilizing a central point, representing alignment

AI-generated image.

Understanding these forces explains why some venues thrive for decades while others struggle to survive their first few years.

The Four Forces of Hospitality Gravity

Four forces shape whether a hospitality brand develops real pull. They operate together, reinforcing or weakening one another over time.

When they align, something powerful happens: guests return, again and again.

Brand Gravity

Brand gravity begins with identity. Not logos, not marketing language, but identity. Venues with strong brand gravity begin with strategic clarity. Operators know exactly what they’re building, and who it’s for.

Guests understand the concept almost instantly: a neighborhood cocktail bar, a high-energy sports pub, a classic steakhouse. The concept doesn’t try to be everything to everyone. Strategic clarity attracts the right guests and naturally filters out those seeking a different experience. Not every guest is meant for every concept. A high-energy nightlife venue and a quiet neighborhood wine bar should not attract the same expectations, behaviors, or occasions.

Alignment is the first step toward gravity. When identity is unclear, everything downstream becomes harder: marketing loses precision, hiring becomes inconsistent, and service standards drift because teams no longer understand what experience they’re protecting. Clear brands make better operational decisions because the business understands itself first.

Strong identity shapes expectations before a guest ever walks through the door. That kind of alignment creates stability. It reduces friction, improves consistency, strengthens culture, and allows teams to deliver experiences with greater confidence and precision. Clear identity strengthens attraction, improves retention, and gives consistency something stable to compound from. Brands that try to appeal to everyone often lose the clarity that made them compelling in the first place.

Social Gravity

When guests connect with a venue, something begins to happen: they talk about it. They recommend it. They bring other people. Gravity spreads socially long before operators recognize it. Stories start forming around the venue. People come on first dates. They celebrate milestones there. Friends gather for late-night conversations. Strangers find common ground at the bar and leave having made a new connection.

These moments transform a business into a place. More importantly, they turn that place into a guest’s place. It becomes their spot, their third space. That emotional ownership matters more than most operators realize. Guests protect places they identify with emotionally. They recommend them differently. They forgive small imperfections more easily, and continue returning even when alternatives exist. That’s the moment a venue stops competing transactionally and starts existing socially inside a guest’s life.

Places with stories travel through social networks faster than any advertising campaign.

Structural Gravity

Identity and buzz can attract attention. That’s important, but that’s just one component of the overall formula. Attention is easier than it has ever been to generate, and it easily devolves into noise. Noise is expensive.

When noise compounds faster than meaning, only what is built to hold will remain. What attracts attention is no longer a reliable indicator of what will sustain the concept. It’s structure that sustains gravity.

Behind every venue that “just works” for guests is a system supporting the experience: operational discipline, training systems, service standards, kitchen consistency… These structures create reliability. Guests trust that the experience they enjoyed last time will exist again the next time they return.

That said, structure does more than just create consistency: it protects the identity of the business under operational pressure. Without structure, standards become reactive. Experiences vary depending on staffing, stress, volume, or leadership presence. Over time, the business slowly drifts away from the experience guests connected with originally. That drift is where gravity begins weakening. Without structure, even the strongest concept eventually collapses.

Gravity Imbalance

The final force appears when one of the others weakens. Gravity rarely disappears at once; it erodes through imbalance. The imbalance often goes unnoticed because performance appears stable. Traffic looks strong, and revenue holds. Meanwhile, erosion is slowly but steadily weakening the structure. That delay creates false confidence.

Operators assume the business is healthy because visible performance hasn’t collapsed yet. But gravity often weakens long before the market response materializes fully. By the time traffic softens noticeably, trust, consistency, and emotional connection may have already been eroding for months. A cocktail bar may have a strong concept but weak operations. A nightclub may generate social buzz but fail to deliver a consistent experience. A neighborhood restaurant may run efficiently but lack a compelling identity. When one force falls out of alignment with the others, gravity weakens.

Guests feel the difference even if they can’t explain it. They visit less often. Eventually, they stop returning at all.

A Simple Diagnostic

Operators don’t need complicated analytics to sense whether gravity exists.

Four simple questions often reveal the answer:

  1. Do guests understand our concept instantly? If guests struggle to describe what your venue is, brand gravity is weak.
  2. Do guests talk about us outside of our four walls? If the venue rarely enters conversation, social gravity hasn’t formed.
  3. Does our operation deliver the same experience every night? If the answer is no, structural gravity can’t hold.
  4. Are these forces reinforcing each other or quietly working against each other? When identity, experience, and systems move in different directions, gravity weakens.

Most operators already know the answers. What they often lack is the framework to interpret what those answers mean. But if they answer these questions honestly, most will understand quickly where the real problems lie.

The Difference

Some venues constantly chase guests, others pull them in. The difference isn’t luck. It isn’t demographics, and it isn’t the latest trend. It’s gravity. It’s brand clarity, social momentum, and operational discipline. When these forces align, something remarkable happens: guests return, again and again.

When gravity forms, retention strengthens. That means marketing becomes more efficient. It means that word of mouth accelerates naturally. Teams operate with greater clarity because the experience they’re protecting is fully understood across the business. The venue stops relying entirely on constant stimulation and begins generating pull organically.

Everything else is noise. And noise is expensive.

Related Reading

Sign up for the KRG Hospitality Pre-Open Sequence emails

by David Klemt David Klemt No Comments

What Breaks Gravity in Hospitality

Why some venues lose momentum even when everything looks right on the surface

In hospitality, some venues pull guests in while others spend their entire existence and valuable resources chasing them.

By now, most operators can recognize the difference. They’ve seen the places that stay busy without constant promotion, and those that rely on a steady stream of new attention just to maintain traffic. They’ve also seen the opposite.

The venues that need another event, another campaign, another push to maintain momentum constantly. The businesses that appear successful publicly while operators quietly feel the pressure internally. Full weekends followed by unpredictable weekdays. Strong visibility paired with weak retention. Over time, those cycles becomes exhausting.

Eventually, those businesses stop growing naturally, instead depending on continuous stimulation just to maintain baseline traffic. This is usually the moment operators begin searching for tactical answers: “better” marketing, new offers, updated branding, fresh programming. And yes, sometimes those things help…temporarily. Unfortunately, temporary momentum and lasting pull aren’t the same thing.

The assumption is usually that the difference comes down to concept, marketing, or budget. It doesn’t. It comes down to something less visible and more fragile: alignment.

by David Klemt

An asymmetrical ripple through an otherwise perfectly aligned series of concentric rings, communicating misalignment.

AI-generated image.

Gravity doesn’t form from a single strength. It forms when multiple parts of a business reinforce each other over time, and weakens the moment they don’t.

When Things “Look Right” but Don’t Hold

One of the most frustrating patterns in this industry is the venue that seems to have everything going for it yet still struggles to build repeat behavior.

The concept is strong, the space is well designed, and the grand opening generated buzz. And yet, six months later, traffic becomes inconsistent. Twelve months later, the team is working harder for weaker results. Eventually, the venue finds itself chasing attention again.

Nothing “broke,” but something stopped holding. That’s the difference most operators miss: gravity doesn’t disappear because of a single failure, it erodes when the underlying pieces stop working together.

Many hospitality businesses appear stronger than they actually are. Good design can disguise weak operations for a while. Social buzz can hide inconsistency, at least temporarily. Strong opening traffic can create the illusion of traction long before true guest loyalty exists. That’s part of what makes gravity difficult to diagnose early.

Modern hospitality is full of venues that look successful from the outside while they struggle quietly underneath the surface. The room looks full. Social media engagement looks healthy. Revenue may even appear stable for a period of time. But attention and attachment are not the same thing. One creates temporary movement, the other creates return behavior.

When a business relies too heavily on visibility without reinforcing the systems, standards, and experiences that sustain trust, gravity begins weakening long before operators recognize it.

The Parts That Must Align

If you look closely at venues that consistently pull guests back, a pattern emerges. That pattern is the revelation of a relationship between a few crucial elements.

Identity

First, the concept is clear. Guests understand what the venue is within moments. There’s no confusion, no hesitation. The identity is strong enough to attract the target audience and filter out people seeking a different experience.

Guests don’t spend time trying to decode whether a venue is for them; they feel clarity almost immediately. The stronger the identity, the easier the decision becomes. Confused brands create friction, clear brands create pull.

Experience

Second, the experience holds. What guests encounter matches their expectations. The experience may not match perfectly, but it does so reliably. The food, the service, the atmosphere… They feel consistent enough to build trust over time.

Consistency matters: trust is built through repetition. Guests don’t return because a venue was excellent once. They return because they believe the experience will reliably meet expectations again. That predictability lowers decision risk. Over time, it becomes part of the venue’s gravity.

Emotional Memory

Third, something sticks. The visit leaves an impression that isn’t necessarily dramatic but is meaningful enough to remember. The venue becomes associated with a moment, a person, or a feeling. Individually, none of these are enough. Together, they create pull.

Most guests don’t remember every detail of a night out. They remember how the experience settled emotionally. They remember how the room felt. How the staff made them feel, who they were with, and what the venue has become associated with in their lives. That emotional “residue,” if you will, is what creates return behavior.

Where It Starts to Break

Problems begin when those elements fall out of alignment. A venue may have a compelling concept but fail to deliver it consistently. Another may run a tight operation but lack a clear identity. Some generate social buzz but don’t create experiences worth repeating.

This is where many hospitality businesses begin confusing visibility with strength. A venue can generate constant content while losing guest trust quietly. It can create excitement while exhausting its team behind the scenes. The place can produce impressive revenue numbers while standards erode slowly underneath operational pressure.

From the outside, these businesses often appear healthy for far longer than they actually are. That delay is dangerous: by the time the market fully feels the instability, the internal damage has usually been compounding for months. From the outside, these issues don’t always look critical. Inside the business, they’re everything.

Guests don’t analyze these gaps, they feel them. And when something feels off, even slightly, behavior changes. Return visits come less frequently. Recommendations from once-loyal guests slow. The venue slips out of regular rotation before it disappears altogether.

This collapse doesn’t happen dramatically, it occurs quietly until the pull is gone.

When Drift Begins

Most venues don’t collapse all at once; they drift first. Standards soften slightly, execution becomes less consistent, small compromises become normalized under pressure. The identity that once felt sharp starts becoming diluted by reactive decisions, chasing trends, or operational fatigue.

None of these changes seem catastrophic individually, and that’s what makes drift dangerous. Guests rarely announce when trust is weakening. They simply return less often. The emotional connection fades gradually until the venue is no longer part of their routine.

By the time operators recognize the shift fully and realize their business is collapsing, gravity has often been weakening for far longer than expected, already reaching a critical level.

Why Operators Miss It

Most operators don’t think in terms of alignment, they think in terms of fixes. That reaction makes sense, to a point. Hospitality trains operators to solve immediate problems quickly. Traffic dropped? Increasing marketing. Reviews have softened? Tighten steps of service. Revenue has weakened? Expand promotions (often accompanied by discounting heavily).

Urgency rewards action, right? The problem is that visible action and meaningful correction are not always the same thing. Most gravity problems aren’t caused by a single broken tactic. They emerge when identity, operations, guest experience, and emotional connection stop reinforcing each other consistently over time. No single promotion fixes that.

Each action taken addresses a symptom, but gravity isn’t a single-variable problem. It’s the result of multiple forces either working together or not. That means solving for one issue in isolation rarely restores what was lost.

A Simpler Way to See It

Busy doesn’t automatically mean meaningful. Some venues generate transactions, others become part of people’s routines, identities, and social lives. That’s where gravity becomes difficult to replace. The great news is that you don’t need complex analytics to recognize whether gravity is forming or fading. A few questions usually make it clear:

  • Do guests understand what we are immediately?
  • Does the experience match that expectation every time?
  • Does the visit leave enough of an impression to bring them back?

If any one of those answers is weak, something is misaligned, and misalignment is where gravity breaks.

But let’s go deeper. A few additional questions tend to reveal even more:

  • Are guests returning naturally, or only after being prompted?
  • Does the marketing reflect the actual guest experience?
  • Are standards holding during pressure, or only during calm periods?
  • Would guests genuinely notice if the venue disappeared?

That last question matters more than most operators realize. It may seem extreme, and the answer may be brutal. However, the answer will help any operator focus their attention on a real strategy rather than wasting time on an ineffectual “fix.”

The Difference

Some venues chase guests constantly, others pull them in. The difference isn’t luck, and it isn’t demographics. It certainly isn’t the latest trend.

The difference is whether the business is working as a unified system or a collection of disconnected parts. Clear identity, consistent execution, and experiences that stay with people. When those elements align, gravity forms. When they don’t, it fades. The market eventually reveals whether a hospitality business is aligned structurally or simply temporarily visible.

Attention can be manufactured for a while, and momentum can be borrowed briefly. But over time, guests respond to coherence. They return to places that consistently reinforce trust, familiarity, emotion, and identity together. That’s what creates pull. Once that pull forms, growth becomes more stable, marketing becomes more efficient, and loyalty becomes more resilient under pressure.

Everything else is noise, and noise is expensive.

Related Reading

Sign up for the KRG Hospitality Pre-Open Sequence emails

by David Klemt David Klemt No Comments

What Actually Creates Gravity in Hospitality

Why some venues pull guests back again and again while others constantly chase attention.

In hospitality, there’s a difference between restaurants, bars, and hotels that attract attention and places that create pull.

Most operators know how to get attention. Fewer recognize what actually makes guests come back without being asked.

Attention is easy to manufacture:

  • A flashy opening
  • A viral cocktail
  • An influencer visit

All of that works. At least, it works for a moment. But attention fades; it always does.

Gravity, however, does not.

Gravity forms when a venue stops being a decision and starts becoming a default. When guests no longer evaluate where to go, but simply go where they already trust the experience will deliver. That’s pull.

That’s the difference most operators miss: traffic can be created but return behavior has to be earned.

Unfortunately, if you’ve spent any time in this industry, you’ve seen the opposite play out.

Operators chase visibility, and when that appears to pay off, they celebrate volume. Then, they invest in what’s loud, new, and easy to boast about in their marketing. Most operators, therefore, don’t struggle because they lack effort. The struggles come from optimizing for the wrong outcomes.

by David Klemt

AI-generated image of a gravity well featuring a dark sphere impacting a dark background grid deepy

Gravity isn’t what moves things once, it’s what shapes everything, continuously. (AI-generated image)

And yet, the venues that actually last—those that stay busy without chasing attention constantly—are usually doing something much less visible: they’re building something that holds.

You see it in every city. The bar that’s always busy, even on off nights. The restaurant guests recommend without being asked, and the café people walk past three competitors to reach.

These businesses don’t just generate traffic, they create pull.

Attention is Temporary. Gravity is Durable.

Many operators chase attention. On the surface, that makes sense: attention is visible.

They can point to an array of visible signals, like packed openings, social media engagement, PR coverage, a new platform that promises reach.

What they’re pointing to feels like momentum, like growth. But that’s on the surface, meaning it’s shallow. Those visible signals aren’t providing helpful insights.

Attention is fragile because it depends on constant input. The moment an operator stops pursuing attention, it disappears.

Gravity works differently: it compounds.

When gravity forms, guests don’t need to be reminded you exist. Your guests don’t need to be convinced to return. They’ve already made their decision (often subconsciously) because the experience fits well into their lives.

That’s why some venues can absorb pressure. Slower seasons, weaker marketing, even small operational missteps don’t break them immediately. They’ve built enough gravity (pull) to sustain demand.

The operators who are constantly chasing attention, meaning they’re dumping valuable and limited resources toward it, haven’t built real pull. Instead, they’re forced to replace every lost guest with a new one, rinse and repeat ad nauseam, because nothing is holding people in place.

While it may sound like a marketing problem, it isn’t; it’s a structural one.

The Forces Behind Gravity

If you step back and look at the venues that pull guests in consistently (attracting first-time guests and converting them into repeat guests), the pattern isn’t random.

When you look closer, the same patterns show up time and time again.

Clear Identity

Venues with gravity know exactly what they are. Not internally, but externally. Not even necessarily what the owner intended but what the guest can understand immediately.

Most positioning in this industry is vague:

  • “Elevated casual dining.”
  • “Chef-driven concept.”
  • “Upscale neighborhood bar.”

These phrases don’t actually help a guest decide anything. What drives the decision to visit once and return is a clear identity.

A guest should be able to describe your venue in a single sentence without thinking. If they can’t, your positioning isn’t working.

Clarity reduces friction, making the decision easy: “This place is for me,” or it isn’t.

When identity is unclear, guests hesitate, and hesitation is the enemy of return behavior.

Consistent Experience

Operators consistently underestimate consistency because it isn’t exciting. There’s nothing viral about repeatedly, daypart in and daypart out, delivering the same great experience.

And yet, that’s exactly what builds trust with guests.

Gravity collapses when the experience becomes unpredictable. Guests notice it when food quality shifts, service varies depending on who’s working, and atmosphere changes depending on the night, even if they don’t or can’t quite articulate it.

They don’t track inconsistency. It’s not like they’re creating spreadsheets and keeping tabs on the consistency of your operation. They just stop coming back as often, or at ever again.

Consistency isn’t about perfection, it’s about reliability. Guests need to know what they’re walking into, and trust that you and your team will meet the expectation you’ve set.

Behind every venue that “just works” for guests is structure: clear standards, defined systems, and teams that know what excellence looks like.

Gravity doesn’t survive without that structure because without consistency, there’s nothing to hold onto; it can’t form.

Memorable Moments

The strongest hospitality brands don’t just serve food or drinks, they create memory.

They become tied to moments like first dates, weekly rituals, and celebrations that matter. Once that connection forms, the relationship changes.

The venue is no longer just a place, it’s part of someone’s story.

That’s when gravity strengthens.

Guests don’t just return, they default to your spot. They stop searching for alternatives. They may check out new places, but you’re always in the conversation during the decision-making stage. You and your team become what society is too often missing these days: their Third Place.

They recommend the venue without being prompted, because it already exists in their mental shortlist of “places that work.”

Most operators assume this comes from marketing. In reality, it comes from memory being reinforced, visit after visit.

Gravity spreads socially long before operators realize it’s happening.

What Destroys Gravity

Most venues don’t lose gravity because something breaks. Gravity is lost when an operator’s focus drifts.

Their attention shifts to the wrong signals:

  • Revenue headlines instead of underlying stability.
  • Generational assumptions instead of actual guest behavior.
  • Shiny technology platforms instead of operational discipline.

None of these are inherently bad, of course. But they become dangerous when they pull attention away from the forces that actually create durable businesses.

Every distraction introduces variability, and variability weakens trust. Once trust weakens, gravity starts to break.

It happens quietly at first, and then all at once.

The Difference

Some venues constantly chase guests while others pull them in.

The difference isn’t luck, and it isn’t demographics. It certainly isn’t the latest trend.

What makes the difference is whether gravity exists or doesn’t.

A clear identity, disciplined consistency, and experiences that stay with people. That’s what creates pull.

Everything else is noise, and noise is expensive.

Related Reading

Sign up for the KRG Hospitality Pre-Open Sequence emails


by David Klemt David Klemt No Comments

Service Failure: A Real Restaurant Experience Through 3 Lenses

We’ve returned from Las Vegas after attending the 2026 Bar & Restaurant Expo, at which Doug Radkey hosted an impactful education session.

Interestingly enough, his session addressed the top eight reasons for the failure rate in hospitality.

On our second evening we had a memorable restaurant experience. Unfortunately, it isn’t memorable because it was so amazing.

There’s something particularly frustrating (if not infuriating) about receiving bad service from a restaurant as a hospitality professional attending an industry trade show event at the host hotel.

Things go wrong, standards slip, and teams need to recover; perfection is an illusion. We’ve all been there, on the service side and the guest side. And we’ve all experienced smooth recoveries on both sides.

Having to recover due to a service drift isn’t the end of the world. In fact, I firmly believe recovery opportunities are valuable coaching moments that can improve the overall operation.

However, when multiple issues arise and zero recovery ever takes place, that’s a problem. There’s just something, as I’ve said, that really makes service failure stand out when one has just left a hospitality industry event during which one has connected with operators, educators, and consultants, walked a few hundred feet down a casino corridor, chosen a restaurant, and received poor service.

The irony of experiencing this hours after presenting a session on the failure rate in hospitality was not lost on us.

Again, these are learning opportunities. So, I’m going to break down the service failure through three lenses. 

by David Klemt

A salad with chicken and Parmesan cheese shavings.

All I wanted was a salad. Not this salad (I never got to see it), but one similar.

Let’s take a look at what went sideways from the guest perspective, coaching opportunity perspective, and strategist perspective.

The Service Failure

Everything started off well. The host stand was helmed by friendly employees. Servers looked like they were on their game.

The restaurant wasn’t slammed but it wasn’t dead; there were several tables available, and most seats at the bar were empty. Great—we asked to sit at the bar, taking a corner seat on the opposite side of the service well.

From that seat, the server stations, corridor to the kitchen, main dining room area, and service bar were in view.

We ordered a cocktail and a beer from the bartender, placed our food orders…and that was the final interaction we had with the bar team until we were ready to pay our bill.

It may seem a bit odd, but as much as I wanted the quesabirria I had ordered, I was really looking forward to the Caesar salad. After a couple of days on the Strip, a morning and afternoon at the Las Vegas Convention Center, and a couple of hours at the Welcome Kickoff Party, something light and refreshing seemed like a great idea.

Unfortunately, that salad never came. Neither did the bartender after serving the single rounds of drinks we managed to order. There was no check-back on the drinks, nor any of the dishes that were dropped off by runners. In fact, the empty glasses were never removed, and the empty plates just sat in front of us, stacking up. And no, the bar wasn’t slammed; we were two of the half-dozen or so guests seated there.

The bartender seemed far more interested in preparing the bar for a close that was about two hours away. Worse, the manager on duty, often posted up at the service well, corrected none of the failure they could clearly see. They were busy expoing drinks, glancing at our empty glasses and plates, and not engaging with us or the bar team. [Note: Busy doesn’t indicate that you’re getting anything done or being efficient. In fact, it can indicate the opposite.]

The Guest Perspective

When a guest receives poor service, they’re not focusing solely on an item they didn’t receive. That’s a huge part of it, of course, but not the whole story.

Their frustration often goes beyond “I didn’t get one of my items.”

Depending on the person, they’ll likely feel a range of emotions and internalize what can be perceived as a personal slight.

Have they done something to start their visit on the wrong foot? Do they look like they don’t belong, somehow? Does the staff not like them for some reason?

Failing to deliver one item, refusing to check back with a guest, and ignoring their attempts to get your attention can easily make a guest feel alienated, irrelevant, and insignificant.

Hospitality is about making everyone feel welcome, relevant, and valued; the focus is on providing serving others. The concept of hospitality is betrayed when we do or say anything that tells a guest they don’t matter, or that they’re not “good enough” to get great service.

I felt none of that, but I’m also in hospitality; I don’t take it personally. I was busy attempting to discover the root cause of the failure and waiting for a recovery that wouldn’t come, beyond the salad that never appeared being taken off the bill at the end of our meal (after I was finally able to address it).

Guests who don’t work in hospitality, on the other hand, may take entirely avoidable service failures personally, leave feeling very much the opposite of welcome, and encourage others to never visit the offending restaurant.

The Coach Perspective

When a person in a leadership role notices standards slipping, the knee-jerk reaction is often to intervene immediately and solve the problem for their team. That’s entirely understandable, particularly when that leader plans to address the drift from standards at the next pre-shift meeting (and follows through on that plan).

That said, some service issues provide an excellent opportunity for leaders to develop a powerful and valuable skill: coaching.

Just as there are differences between strategists, consultants, and coaches, there are notable differences between managing and coaching.

Managers use direct, one-way communication; they tell the people who report to them what to do. When it comes to standards drifting, they tend to solve the problem for the team. (Good and great managers also take responsibility for the drift.)

Coaches use two-way communication to guide an individual to find the solution on their own. In that way, they develop people, empower them, and are often excellent mentors.

Ideally, a hospitality team’s leaders are managers and coaches, knowing when to leverage the strengths of both roles.

Had the MoD at the restaurant noticed our empty glasses, which we had slid across to the edge of the bar next to our empty plates, he may have pulled the bartender aside for a moment. In a coaching role, he could have asked a simple question: “What’s going on with Seats 1 and 2?” or “What do you see at 1 and 2?”

Either question would have told the bartender the MoD had spotted an issue and expects them to figure out what it is. That would also have told the bartender they need to reset and focus on guest service. Such a simple coaching move can help build a sharper, more engaged team.

Coaching redirects work for every role in the house, and they’re more powerful than many operators and their leaders may realize.

The Strategist Perspective

I’m more disappointed in the failure of the MoD to intervene than I am the bartender. And the fact that the bartender working service well didn’t intervene while the MoD was expoing drinks tells me a lot about the restaurant’s culture.

The service well bartender absolutely noticed our empty glasses and plates, and turned away when eye contact was made. If they saw me try to get their attention, they felt comfortable ignoring me by stepping to the other side of the bar, breaking sight line via the center back bar.

I’m not going to snap my fingers or raise my voice to get a bartender or server’s attention; the former is horrific, and the latter isn’t a pleasant guest experience. If my direct “excuse me” is ignored a few times, I’m going to enter assessment mode, settle in, and observe how the team works, with a focus on the venue’s leadership.

The service bartender also didn’t feel the need to say something to their peer who was supposed to be serving guests, or felt uncomfortable doing so. And the bartender who had (barely) served us was clearly quite comfortable ignoring two guests in front of the MoD, who could also see that we were not having a great experience.

Instead, when not rushing to the back of house, that bartender busied themselves with cleaning and straightening behind the bar. Interestingly, none of that busy work involved our section of the bar.

As the person in a leadership position, I place the responsibility for service failure entirely on the MoD. If they were the GM, the restaurant is flying a flock of red flags. If the issue is this one manager, the rot still runs deep; the team has learned that standards can drift when that manager is running the show.

Going deeper, that means the damage is done. If standards drift when one manager is on, poor habits don’t just disappear when a different manager is overseeing the restaurant. Instead, some team members (at least two that I can think of at this restaurant) learn how to hide their bad habits depending on which manager is working their shift. The culture needs to be addressed, starting with considering and reflecting on values, deciding on the non-negotiables, documenting SOPs clearly, and training on them, starting with the leadership team.

This restaurant team has likely learned that standards where they work are negotiable, which means they’re not standards at all. If they’re not standards, they’re just recommendations. And if what’s expected isn’t enforced as a true standard, the operation isn’t run by systems, it’s plagued by inconsistencies.

None of that leads to success.

Image: Raphael Nogueira via Unsplash

Related Reading

Work with Us

Click the image below to learn about our services, how easy it is to work with KRG Hospitality, and how we can help you with your concept.

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Three Lies Hospitality Operators Need to Stop Telling Themselves

Revenue vanity, generational myths, and the expensive distractions hurting operators.

The hospitality industry spends an extraordinary amount of time talking about the wrong things.

Operators debate generational stereotypes. They brag about revenue numbers, and chase the newest technology platform.

Meanwhile, the operators who actually build durable businesses are focused on something far less exciting: structure, discipline, and profit.

Spend enough time walking trade show floors, reading hospitality headlines, or sitting through conference panels and the pattern becomes impossible to miss.

Hospitality doesn’t suffer from a lack of passion; it suffers from distraction.

And some of the loudest conversations in the industry right now are built on myths that waste operators’ time, money, and attention.

by David Klemt

A closeup image of a hand attached to the leads of a lie detector, with the small polygraph machine sitting on the bar top.

Illustration generated using AI

Here are three of the worst lies distracting operators.

Lie #1: Sales Equals Success

Revenue is hospitality’s favorite number. Or, phrased a bit differently, sales are hospitality’s favorite vanity metric.

Operators proudly announce they’ve done $3 million or $5 million in annual sales. Trade show rooms applaud when they hear big sales numbers. Social media celebrates. Award nominations start rolling in. Hospitality publications write features.

But revenue alone tells you almost nothing about whether the business is healthy.

A venue doing $3 million in sales and netting $100,000 isn’t a success story. It’s really a stressful job disguised as a business. A significant number of hospitality entrepreneurs end up giving themselves jobs instead of building businesses and empires.

Sales tells you how busy you were. Profit tells you whether your model actually works.

Too many operators chase volume (full dining rooms, long lines, packed weekends) because volume looks impressive. However, the reality is busy doesn’t equal profitable.

Busy rooms and long lines look impressive to some. But profitability, not popularity, is what determines whether a business survives.

The operators who survive long-term aren’t chasing top-line numbers, they’re protecting margins.

Lie #2: Generations Explain Everything

Another long-standing distraction is the industry’s obsession with explaining everything through generational stereotypes.

We’ve read and heard them all: Boomers are entitled, Millennials have killed restaurants, and Gen Z doesn’t drink.

Did you notice I skipped Gen X? That happens a lot when discussing generations.

These narratives make for easy articles and viral social media posts. However, they rarely reflect what operators actually see inside their venues.

Guests aren’t demographic caricatures, they’re people.

Yes, preferences evolve. But successful operators pay attention to how guests behave in their rooms, not how someone online claims an entire generation behaves.

When operators get distracted by generational mythology, they miss the fundamentals that have always mattered: hospitality, atmosphere, consistency, and value. They also miss another key factor when serving people: speaking to guests’ personal values.

Hospitality doesn’t need better stereotypes; nobody and no industry does. Hospitality needs better observation.

Lie #3: Critical Thinking is Optional

This is where the industry’s most expensive mistakes happen.

Operators will hesitate to invest $30,000 in strategic planning that could protect hundreds of thousands or millions of dollars in capital. But they’ll sign a $50,000 equipment order without blinking.

Operators will overspend on technology platforms they barely use. They’ll chase design trends that photograph well but do nothing for the business. They’ll throw open their doors and add complexity before they’ve built stability.

It happens constantly.

People under-invest in critical thinking and over-invest in shiny equipment, overpowered tech, and unnecessary design.

The irony is that thinking—strategic clarity, concept development, operational structure, financial discipline—is the part that determines whether a venue survives.

Equipment doesn’t fix a weak concept, technology doesn’t repair broken operations, and beautiful interiors don’t create profitability.

You know what does tick all those boxes? Systems and structure.

The Reality

Bars, restaurants, nightclubs, eatertainment, hotels, and every hospitality business in between rarely fail because operators lack passion.

They fail because operators chase signals that look impressive and buy into stereotypes disguised as actionable data points. Failure comes because they’re distracted by revenue headlines, generational myths, shiny equipment, trendy technology, and, possibly the most damaging of all, refusing to change because “we’ve always done it this way.”

If these distractions dominate so much operator thinking, what’s the answer to this key question: What really creates truly durable hospitality brands?

Signals that actually matter.

The operators who build durable businesses focus on something much less glamorous: building businesses with real pull.

They develop and build out clear concepts. They adhere to disciplined operations, and implement profitable systems.

Everything else is noise, and noise is expensive.

Related Reading

Work with Us

Learn how we can help you cut through the noise and receive strategic clarity on your hospitality project. Click the image below!

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

2026 Pizza Industry Trends: Styles, Ingredients, Pricing, and Strategy for Operators

There are 75,736 pizzerias operating in the United States right now. Together, they generate an estimated $49.6 billion in annual revenue despite a slight (0.3%) dip year over year, according to IBISWorld.

Meanwhile, 86 percent of Americans ate pizza or flatbreads in 2025, and 40 percent of Gen Z consumers are eating pizza at least once per week.

Demand isn’t the issue; competition is.

Pizza is one of the most democratic menu items in hospitality. It works in a 20-seat neighborhood bar, a 200-seat restaurant, a food hall, a hotel lobby, a stadium concourse, or a multi-unit chain spanning multiple states… Pizza even works via automated vending machines.

It thrives at lunch, during a beer-and-shot-soaked visit to a dive bar, and over late-night cocktails. That said, ubiquity is a double-edged sword.

When nearly everyone sells pizza, differentiation—not dough—becomes the battleground.

Reports from Pizza Today, PMQ Pizza, IBISWorld, and Datassential show competition shifting beyond style and price toward positioning, operational precision, retention, and tech fluency.

Detroit and tavern-cut are surging, hot honey and Calabrian chiles are climbing. Anchovies and sun-dried tomatoes may be sliding. The average large cheese pizza now sits at $16.92 nationally, with some regions pushing past $20.

Data alone doesn’t answer the structural question: How do you turn pizza’s mass appeal into brand gravity? The real structural question is: How do you turn pizza’s mass appeal into brand gravity?

Going further: How do you convert one-time traffic into repeat behavior after investing to acquire it? And how do independents win when chains can often absorb margin pressure more easily?

Let’s break down what the 2026 pizza data actually means for independent operators.

by David Klemt

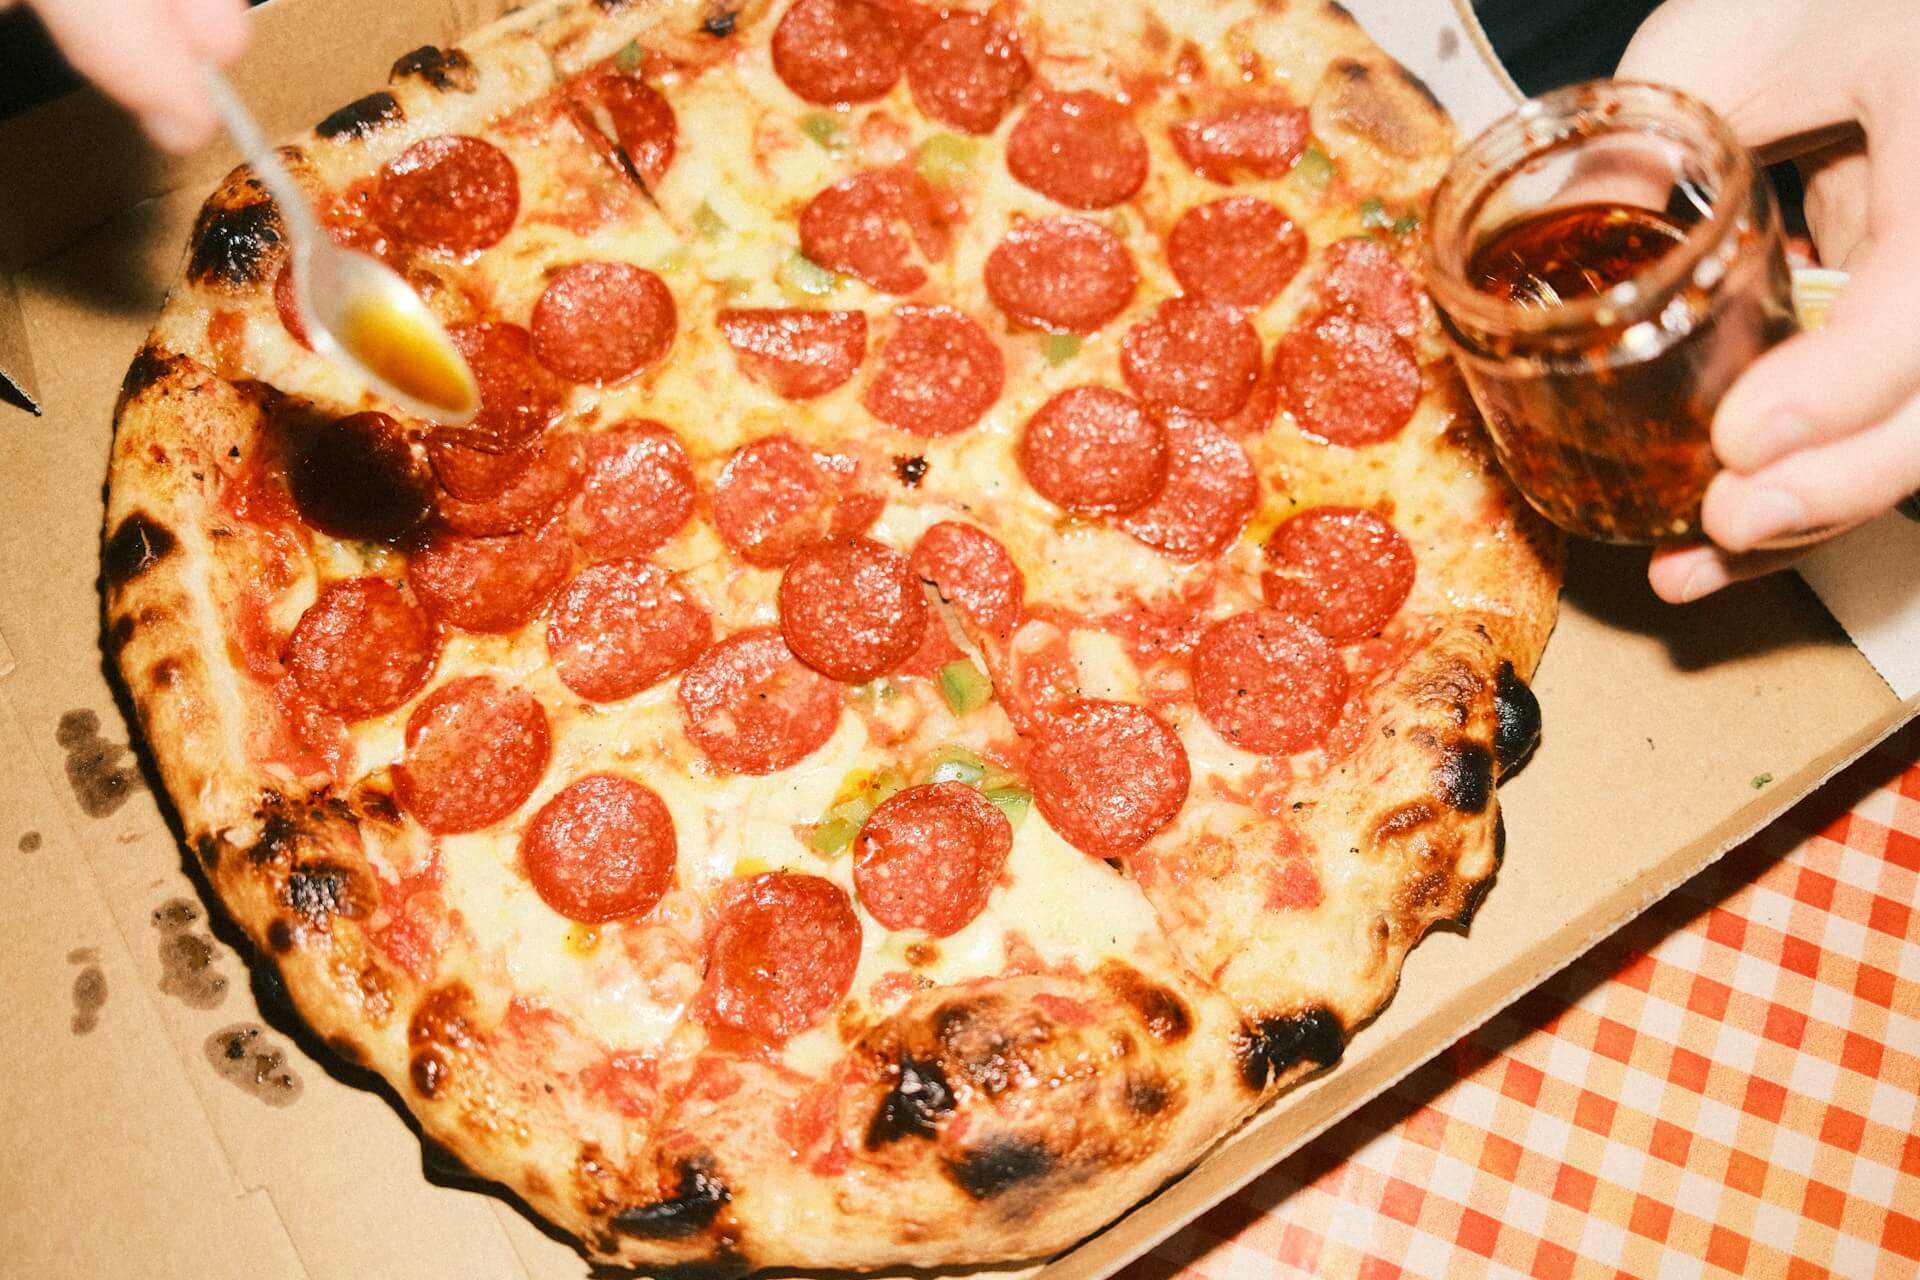
Drizzling hot honey onto a pepperoni pizza

Pepperoni and hot honey are hot ingredients heading into 2026.

Top Pizza Styles in the US

Pizza Today

  1. New York
  2. Traditional American
  3. Chicago Thin (including Tavern)
  4. Detroit
  5. Neapolitan/Neopolitan
  6. Sicilian
  7. Deep Dish
  8. Grandma
  9. California/American Artisan
  10. Roman

Hot Pizza Styles in the US for 2026

Pizza Today

  1. Detroit
  2. New York
  3. Chicago Thin (including Tavern)
  4. Deep Dish
  5. Sicilian

Datassential

  1. Chicago Tavern-Cut
  2. Detroit
  3. Brick Oven
  4. Chickpea Pizza Crust
  5. Flatbread Pizza
  6. Neapolitan
  7. New York

Top Pizza Ingredients

Pizza Today

  1. Pepperoni
  2. Sausage
  3. Mushroom
  4. Bacon
  5. Onion
  6. Extra cheese
  7. Chicken
  8. Black olives
  9. Canadian bacon
  10. Jalapenos
  11. Ham
  12. Red/Green pepper
  13. Meatballs
  14. Pineapple
  15. Basil
  16. Beef
  17. Fresh garlic
  18. Banana peppers
  19. Spinach
  20. Artichoke

Datassential

  1. Plant-based pepperoni
  2. Pepperoni
  3. Mozzarella
  4. Tomato
  5. Mushroom
  6. Sausage
  7. Chicken
  8. Peppers
  9. Bacon
  10. Garlic

Hot Pizza Ingredients on the Rise in 2026

Pizza Today

  • Brisket
  • Calabrian chili pepper
  • Chorizo
  • Figs
  • Nduja
  • Pistachios
  • Ricotta

Datassential

  1. Plant-based pepperoni
  2. Hot honey
  3. Pepperoni cups
  4. Paneer
  5. Dill pickle
  6. Honey
  7. Calabrian chili pepper
  8. Barbecue pork
  9. Mint
  10. Cotija

Ingredients on the Decline in 2026

According to Pizza Today, most pizzeria operators (at least among those they surveyed) aren’t planning on pulling any ingredients from their menus.

Some respondents are indeed planning to ditch a number of toppings this year:

  • anchovies
  • artichokes
  • shrimp
  • sun-dried tomatoes

It’s likely these eliminations are due to price increases.

Pricing Across the US

PMQ Pizza analyzed pizza trends and data, including pricing.

They engaged Slice, the app that for several years released their own Slice of the Union report, for several data points. I used to look forward to this study each year, but Slice appears to have stopped releasing their report after 2024.

One of the bits of info PMQ asked Slice to provide is the average price for a large cheese pizza. On average, a large cheese pizza costs $16.92 in the States. That said, pricing can be region-specific.

In New England and on the East Coast, a large cheese pizza is under the national average, ringing in at $16.71 and $16.82, respectively.

Moving to the Central US, that price climbs to $17.10. A large cheese pizza, on average, costs $20.17 on the West Coast.

How to Win with Pizza in 2026

It’ll take more than keeping up with pizza style and topping trends to with pizza.

This is particularly true for independents going up against regional, national, and global chains. Chains can often weather rising costs more easily than independents.

Get Personal & Meaty

You likely already have a lunch-daypart-focused menu. It’s possible you’ve even dialed your operation into the snack space, a growing and important revenue driver.

If so, you’re already offering pizza by the slice or personal pizzas. That means you’re well positioned to succeed by tempting proteinmaxxers, diet-conscious guests, and guests on GLP-1 weight loss drugs.

Another way to leverage the trend toward boosted protein consumption is to promote your meat-lover’s pizza.

Cool It

Frozen pizza from independents isn’t exploding, but it is growing. PMQ Pizza has taken note of a handful of indie pizza operations that have managed to take their pizzas nationwide via frozen (and refrigerated) pies.

Indies interested in doing the same can reach out to local retailers, a suggestion made by PMQ Pizza. If doing so proves successful, scale from local stores.

Focus Your Marketing

Pizza Today addresses effective and ineffective marketing techniques in their 2026 Pizzeria Industry Trends Report.

Split into two categories, marketing strategies with less to no effectiveness and strategies with moderate to high effectiveness, the pizza publication helps operators focus their time and resources.

For example, it may be time to consider ditching:

  • flyers
  • direct mail
  • search ads
  • door hangers
  • billboards
  • public relations or press releases
  • geofencing
  • radio ads
  • TV ads
  • magazine ads
  • newspaper ads

Some of the above are more costly than others. If you’re using any of these without seeing ROI, redirect time and money toward higher-performing channels.

Pizza Today identifies social media advertising, word of mouth, loyalty programs, community/sporting events, email, text, video marketing, in-store advertising, and social media influencer campaigns as marketing approaches with moderate to high effectiveness.

Lasering in on loyalty programs, both the Pizza Today and PMQ Pizza reports encourage the development and implementation of this marketing tool. As any operator knows (or learns quickly), guest retention is much less expensive than guest acquisition.

So, focus on transforming first-time guests into valuable repeat guests. Build out a loyalty program, ensure you have a website and that it’s easy to find and use (fast, stable, intuitive, easy to customize orders, etc.), and try to convert most of your traffic into online orders. Free up your phone lines and you’ll likely find you’re capturing more orders and decreasing labor costs, keeping your teams working on more lucrative elements of the operation.

Tighten Your Tech Stack

PMQ Pizza’s 2026 Pizza Power Report includes a checklist on its last page. Using it, you’ll be able to easily identify where your tech stack is strong, where there are gaps, and what to focus on to truly dial it in.

Does every other tool or platform in your stack integrate into your POS? Do you own your online ordering and delivery functions, or are you still using Uber Eats and DoorDash (and losing money, data, and control)?

Is your stack collecting, parsing, and giving you deep, data-rich insights? If so, do you know how to find relevant data, generate useful reports, and track your inventory, other costs, analytics, KPIs, etc.?

And, bringing up everyone’s favorite two letters, are you implementing AI? I’m not asking you to replace humans—that remains a red line for me. Instead, I’m asking you to consider where AI can safely and responsibly streamline your operations, ensure you’re not missing orders, and help control your costs.

Hospitality-focused AI tools can monitor your inventory and automatically place or adjust orders, make staffing more efficient and less costly, and help you implement, optimize, and automate your marketing efforts.

This checklist alone is worth downloading PMQ Pizza’s 2026 report. In fact, I encourage operators to download and review each report directly:

Related Reading

Image: Jay Wennington via Unsplash

Work with Us

Click the image below to learn how we can help you start, stabilize, or scale your pizzeria, restaurant, or bar. Cheers!

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Spectacle ROI vs Scene Retention: The Two Financial Logics of Nightlife

One of the biggest misunderstandings in modern nightlife is assuming the business runs on a single economic system. It doesn’t.

A sold-out Saturday doesn’t mean your model works, it just means your event worked.

What looks like one category from the outside is actually operating on two fundamentally different financial logics. Some venues run on Spectacle ROI, monetizing attention in spikes through high-impact nights. Others run on Scene Retention, monetizing repeat behavior through habit, identity, and belonging.

Both models can succeed. However, they require different strategies, risk tolerance, and expectations.

Nightlife hasn’t just split culturally, it has split economically.

by David Klemt

A DJ performing from an elevated both, with lights and fog going off over the crowd

Spectacle ROI: The Event Model

Spectacle-driven venues operate like live events.

Revenue is concentrated into big nights, big bookings, and big production. Talent becomes a headliner rather than background. Lighting, visuals, and room energy are core parts of the product. VIP sales function as a structured access economy.

The goal isn’t consistency, it’s impact.

Spectacle venues are built to answer one question: How big can this night be?

When this model hits, it hits hard; a single night can outperform several average weeks. The upside per activation is significant.

The trade-off is structural. Spectacle relies on novelty, meaning programming must refresh constantly, and attention fades faster than loyalty. Without momentum, gravity weakens quickly.

Scene Retention: The Habit Model

Scene-driven venues operate more like cultural infrastructure.

Revenue comes from repeat behavior, not single-night spikes. Guests return because the space feels familiar, aligned, and socially meaningful. Programming cadence matters more than headliner scale, and identity and community replace spectacle as the primary draw.

The question here isn’t how big the night can be, it’s how often the same guests return.

The Scene model builds more slowly than its Spectacle counterpart. This model rarely produces explosive revenue peaks. The retention that the Scene model generates compounds: loyalty stabilizes revenue, and acquisition pressure drops. The venue becomes part of a guest’s social routine, not just an occasional destination.

Scene doesn’t monetize moments, it monetizes habits.

The Revenue Split in Plain View

Spectacle operates on ROI (or ROE, return-on-event, more explicitly); Scene operates on retention.

One monetizes attention in spikes; the other builds gravity that compounds over time.

That difference shows up everywhere operationally.

The Nightlife Revenue Split

Dimension Spectacle ROI Model Scene Retention Model
Core Goal Maximize revenue per night Maximize guest lifetime value
Economic Engine Event spikes Habit formation
Revenue Pattern Volatile, high peaks Stable, compounding
Guest Motivation Occasion, visibility Belonging, familiarity
Programming Strategy Big moments Consistent rhythm
Marketing Focus Reach, hype Relationship, trust
Risk Profile High Moderate to low
Talent Dependency High Moderate
Growth Style Fast, unstable Slow, durable
Gravity Source Novelty Habit

Neither model is “better” than the other. They’re built for different environments, capital structures, and operator skill sets.

Where Operators Get Into Trouble

Most struggling venues aren’t failing nightlife, they’re failing model and strategic clarity.

Examples show up everywhere:

  • Spectacle-scale buildout with mid-tier programming.

  • Big DJ nights layered onto a space that lacks identity.

  • Strong community concept buried under overhead designed for event economics.

These are structural mismatches.

You can’t run event economics on retention demand. You can’t expect habit behavior in a room designed for episodic spectacle. And you can’t out-market a model mismatch forever.

Diagnostic: Which Business Are You Actually Running?

Operators often think they’re running as one model while their numbers say they’re operating under another. The checklist below is a reality check.

Spectacle ROI Signals

  • ☐ Our biggest nights drive a disproportionate share of revenue

  • ☐ Talent bookings influence weekly performance heavily

  • ☐ Marketing cycles revolve around specific dates or headliners

  • ☐ Guest traffic varies dramatically week to week

  • ☐ VIP/Table sales are a primary profit engine

  • ☐ Production value is central to guest expectations

  • ☐ Without programming refresh, attendance drops fast

  • ☐ We rely heavily on new guest acquisition

  • ☐ Guests talk about specific nights more than our actual venue/brand

  • ☐ Our revenue model depends on scale and volume

If you’ve checked six or more boxes, you’re operating a Spectacle ROI model.

Scene Retention Signals

  • ☐ Regular guests attend multiple times per month

  • ☐ Staff recognize frequent guests

  • ☐ Programming cadence matters more than individual bookings

  • ☐ Week-to-week revenue is relatively stable

  • ☐ Word-of-mouth outperforms paid promotion

  • ☐ Guests describe our venue as their “spot”

  • ☐ Community identity matters (music, culture, subculture)

  • ☐ Nights feel familiar but still engaging

  • ☐ Loyalty drives traffic more than hype

  • ☐ The business could survive a week without headline talent

You’re operating a Scene Retention model if you’ve checked six or more boxes.

The Red Zone

If both sections score high, you may be trying to operate two incompatible economic systems in one space. That’s where identity confusion, overhead mismatches, programming inconsistency, and marketing inefficiency tend to show up.

This is a red flag, and your reality check, particularly if you feel like you’re working hard but not gaining traction. The issue likely isn’t effort, it’s alignment.

Where Gravity Lives

Spectacle captures attention, Scene builds gravity.

Gravity reduces acquisition pressure. It stabilizes revenue and increases guest lifetime value. Without it, venues remain stuck in perpetual re-acquisition mode, always chasing the next spike and new, first-time guests.

That doesn’t make Spectacle wrong or a “bad” model; it means Spectacle is a different business.

The Decision That Shapes Everything

Before programming calendars, deciding on talent budgets, or developing marketing plans, operators need to answer one question: Are we built to maximize nights or years?

The answer shapes staffing structure, pricing strategy, programming cadence, capital planning, and growth expectations.

Clarity here doesn’t limit a concept, it lays it a stable operating foundation on which a successful legacy brand can be built.

Nightlife hasn’t just fragmented socially; it has separated into two financial logics. Operators who understand which model they’re actually running and stop trying to be both are the leaders positioned to build nightlife brands with real staying power.

Related Reading

Image: Matty Adame via Unsplash

Work with Us

Click the image below to partner with KRG Hospitality on your nightlife project.

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

When Nightlife Becomes an Industry: Spectacle Economics in the U.S.

The U.S. shows what happens when Spectacle Nightlife reaches full maturity: the category shifts from subculture to structured entertainment economy.

Over the past several years, nightlife hasn’t just gotten bigger in the U.S., it has become an industry all its own.

In cities like Las Vegas, a club night can carry the economics of a touring concert, the sales structure of luxury hospitality, and the marketing engine of a major event.

This isn’t nightlife as Scene, it’s nightlife as Spectacle infrastructure. DJ bookings become headline acts, VIP ecosystems become core revenue engines, and venues function less like local scenes and more like recurring live-event platforms.

Understanding this shift isn’t about monitoring trends, it’s recognizing how scale changes the economics, risks, and operating realities of going out.

by David Klemt

Female DJ on the decks, overlooking a nightclub crowd bathed in red light

There was a time when nightlife was primarily a cultural business with entertainment layered into operations and programming.

In the U.S., that equation has flipped.

Today, top-tier Spectacle Nightlife operates at the intersection of three systems:

  • Live-event economics: headliner-style bookings, one-night performance stakes

  • Luxury hospitality mechanics: tiered access, service levels, status signaling

  • Entertainment production logic: lighting, staging, sound, and visuals as core product

This reality goes beyond just running a “busy club.” These venues are now functioning as recurring event platforms.

The DJ is no longer in the background, they’re the headliner. Production is no longer atmosphere, it’s the expectation. VIP is no longer a side offering, it’s the revenue engine.

That is industrialization.

Las Vegas: The Fully Realized Spectacle Model

If you want to see the Spectacle model built out fully, you look to Las Vegas.

Vegas has proven something the rest of the industry now studies and tries to emulate at varying scales: nightlife can be engineered like a large-scale entertainment product when tourism volume, capital investment, and talent pipelines align.

Here, a single night can resemble a festival set compressed into a room (or pool deck, or rooftop, or…):

  • internationally known DJs

  • large-format LED installations

  • choreographed lighting and visual sequences

  • host-driven VIP ecosystems functioning like parallel sales forces

Guest segmentation isn’t incidental, it’s strategic. General admission, elevated GA, table service, VVIP… Each tier represents a different product, not just a different price.

Vegas didn’t simply grow its clubs, it has built a repeatable Spectacle machine.

Spectacle Beyond Vegas: Markets Scaling the Model Differently

While Las Vegas is the clearest example of industrialized Spectacle Nightlife, it isn’t alone.

Other U.S. cities have developed variations of the model. Some may operate at a slightly reduced scale but they’re still built around visibility, production, and high-value guest segmentation.

Miami: Spectacle as Lifestyle Infrastructure

In Miami, nightlife merges with tourism, luxury culture, and 24-hour energy.

Venues like E11EVEN Miami demonstrate how Spectacle logic travels outside Vegas: performance-driven environments, celebrity DJs, VIP ecosystems, and branding that positions the club as a destination in itself. The club even has its own lifestyle clothing brand, with its own dedicated website.

Miami’s version of Spectacle is less about mega-scale venues and more about allure, visibility, and proximity. That said, the economics still revolve around tiered access, production value, and guest perception of status.

Lesson: Spectacle doesn’t need Vegas volume if the city already functions as a global playground.

New York: Spectacle Under Density Pressure

New York City supports both Scene ecosystems and Spectacle venues, but its Spectacle model operates under different constraints: real estate costs, licensing limits, and neighborhood density.

Large-format nights still exist, but the economics require sharper programming, faster turnover of what’s “hot,” and stronger marketing engines. In NYC, Spectacle must fight harder for attention because the city’s overall entertainment field is so crowded.

Lesson: Spectacle in dense urban markets becomes a momentum business: constant refresh, constant visibility.

San Francisco: Spectacle Facing Structural Headwinds

San Francisco shows what happens when Spectacle-style nightlife meets demographic and economic pressure.

Large, generalized club formats have struggled as population patterns and social habits shift. The result isn’t the disappearance of nightlife, but a reduction in the viability of broad, mainstream Spectacle venues.

Markets like this expose a key truth: Spectacle requires the right ecosystem (population flow, tourism, and nightlife culture density) to remain sustainable.

Lesson: Without structural support, Spectacle struggles to maintain gravity.

What Scale Changes

When Spectacle scales to this level, the rules of nightlife shift.

1. Programming Becomes High Stakes

In smaller scenes, a soft lineup might dent a week. At industrial Spectacle scale, one weak booking can impact staffing efficiency, beverage forecasts, and margin performance in a single night.

Talent becomes a cost center that must perform like an asset.

2. Operating Costs Reshape Risk

Between talent fees, production crews, technical systems, security, and host teams, the cost structure resembles event production more than traditional bar operations.

Profitability depends on volume, pricing power, and consistent demand. This model rewards scale, and punishes inconsistency.

3. Marketing Becomes Infrastructure

Promotion is no longer a tactic, it’s a crucial system.

Hosts, promoters, influencer networks, partnerships, and digital campaigns function as a distributed sales and awareness engine. Without it, the machine stalls.

4. The Middle Gets Squeezed

At this scale, the market tends to split into true Spectacle venues, and everything else.

Mid-sized concepts that borrow the look without the engine and gravity often struggle to justify their position.

The Trade-Off of Spectacle at Scale

Industrial Spectacle Nightlife delivers destination pull, global brand visibility, massive revenue potential, and talent relationships that feed future programming.

However, this scale also compresses cultural cycles.

When production value rises everywhere, differentiation must move faster. Trend lifespans shorten, talent dependence deepens, and fatigue sets in more quickly if the experience feels interchangeable.

The more nightlife behaves like industry, the less room there is for cultural ecosystems that are slower to grow to define the mainstream.

The Counterweight: Scene Nightlife in the U.S.

Even in the U.S., Spectacle isn’t the whole story. If Spectacle represents nightlife as industry, Scene represents nightlife as cultural infrastructure.

Further, Scene nightlife isn’t limited to “small” or “secondary” markets, it’s simply the counterweight.

In places like Brooklyn, Chicago, and Detroit, Scene Nightlife operates on a different economic model. The model is defined by lower production arms races, deeper musical or cultural identity, and repeat behavior driven by belonging rather than visibility.

However, these spaces aren’t anti-Spectacle. Instead, they simply monetize a different currency: loyalty rather than volume.

This is the same structural split visible in Canada (and elsewhere), just with greater economic extremes on the Spectacle side in the U.S.

Chicago: Scene as Heritage and Habit

Chicago operates on deep musical lineage and neighborhood ecosystems. House music culture, live music venues, and genre-driven nights create repeat behavior grounded in identity, not production scale.

Chicago’s nightlife isn’t built around Spectacle-motivated spikes, it’s built around weekly rhythms that feel owned by the community.

This is where I first experienced nightlife, from the city’s biggest and most (in)famous nightclubs to goth and industrial bars, and everything in between. Chicago’s Scene Nightlife shaped a significant portion of who I am today.

Detroit: Culture Over Flash

Detroit remains one of the clearest examples of Scene logic. Techno heritage, intimate venues, and music-first environments make nightlife feel participatory rather than performative.

The value isn’t in flashy visual production. In Detroit, the value is in credibility.

Brooklyn: Scene at Urban Scale

Brooklyn demonstrates how Scene can operate at significant size without losing identity. Music-driven venues, warehouse-style events, and culturally specific nights build followings based on trust and consistency.

Brooklyn shows Scene doesn’t mean small. The reality is that Scene Nightlife in Brooklyn is anchored in culture first, scale second.

Portland: Micro-Scene Density

Portland thrives on personality-driven nightlife: themed venues, alternative events, and subculture-specific programming. These rooms rarely compete on spectacle; they compete on character.

This is nightlife designed for people who already know why they’re there, who want to be present, and who value experience over exposure.

Denver: Experience Reframed

Denver shows how Scene evolves with guest behavior. Social events, live music, and alternative nightlife formats emphasize connection, pacing, and community over traditional late-night spectacle.

Here, nightlife behaves less like a production and more like shared experience infrastructure.

What This Means for Operators

When considering starting a nightlife venue, the most important decision by operators isn’t design style, it’s business model identity.

The Spectacle Nightlife model operates on ROE: return on event. Scene Nightlife operates on retention. One monetizes attention in spikes, the other builds gravity that compounds over time.

Dimension Spectacle Nightlife Scene Nightlife
Economic Driver Event revenue spikes Repeat visit frequency
Financial Logic Return on event Retention/Lifetime value
Guest Motivation Visibility, energy, occasion Belonging, familiarity, identity
Programming Model Big nights, headline draws Consistent cadence, trusted rhythm
Risk Profile High volatility Lower volatility, slower growth
Marketing Focus Momentum and reach Community and trust
Gravity Source Hype cycles Habit formation

If You’re Playing Spectacle at Scale:

You are in several businesses at once: the event business, the talent business, and the luxury access business.

To ensure you succeed in Spectacle Nightlife, you need capital depth, programming pipelines, partnerships, and risk tolerance.

This is a high-reward, high-volatility model.

If You’re Not:

Attempting to replicate Spectacle aesthetics without Spectacle economics is incredibly dangerous.

Most markets can’t support industrial-scale nightlife infrastructure. Therefore, following the logic, many are better suited to Scene logic: identity, community, programming cadence, and repeat behavior.

Clarity on how to execute the Scene Nightlife model will help an operator create gravity (the invisible force that pulls the right guests back, again and again).

The Bigger Picture

The U.S. demonstrates what happens when Spectacle Nightlife reaches full economic maturity.

It’s impressive, there’s no doubt it. I’ve witnessed the evolution and industrialization of nightlife in Las Vegas firsthand for nearly two decades.

It’s engineered. Successful Spectacle Nightlife venues are systemized fully, with ruthless precision; nothing is left to chance.

Importantly, it’s also profitable. There are venues that boast nine-figure revenue generation annually.

However, it also makes the defining divide clearer than ever: nightlife today is built either for scale and visibility or depth and belonging.

Operators who understand which business they’re really in—and stop pretending they’re in both—are the industry leaders positioned for longevity as the economics of going out continue to evolve.

Related Reading

Image: Kemal Can via Pexels

Work with Us

Click the image below to partner with KRG Hospitality on your nightlife project.

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Canada’s Nightlife Split: Spectacle vs. Scene, and What it Means for Operators

Closures don’t kill nightlife, sameness does. Across Canada’s major cities, nightlife isn’t disappearing, it’s sorting itself.

What used to be a broad middle ground of bars and clubs for everyone is fragmenting into two distinct operating models.

A recent cultural critique described nightlife as splitting between highly visible, algorithm-feeding spectacle and darker, more immersive underground spaces built for experience over exposure. (Indeed, a number of nightclubs and nightlife venues have dance floor phone bans in place to protect at least one element of the guest experience, and keep people present.) It’s a sharp observation.

For operators, this isn’t about aesthetics or vibes. Nightlife operators need to understand how attention works now, how guests behave inside venues, and what really drives repeat behavior. What we’re seeing is a structural divide: Spectacle Nightlife vs. Scene Nightlife.

This split isn’t uniquely Canadian. It’s visible in major nightlife markets across the U.S. and globally. However, Canada’s cities offer a particularly clear view of how the two models compete and coexist.

Canada’s nightlife markets are a live case study on how these two models, Spectacle and Scene, compete, coexist, and succeed differently.

by David Klemt

DJs performing in tandem or back-to-back inside dark a nightclub.

The Structural Split: Spectacle vs Scene

Spectacle Nightlife

Spectacle nightlife is built for visibility.

These are high-energy, high-production environments designed to deliver moments, visually, socially, and culturally. They thrive on:

  • scale

  • lighting and production

  • social media momentum

  • “who’s hot tonight?” dynamics

Guests don’t just attend these venues and curated events. They perform in their own right, for friends, strangers, and, undeniably and increasingly, for the feed. The room is part dance floor, part stage.

From an operator standpoint, Spectacle Nightlife typically means:

  • higher buildout and operating costs

  • constant programming refresh to avoid fatigue

  • strong marketing engines

  • volatile relevance curves (big spikes, fast drop-offs)

When it works, it prints. When it fades, it fades fast.

Scene Nightlife

Scene nightlife is built for immersion.

These spaces are less about being seen and more about being there, and being present in the moment. The focus is on:

  • music or cultural identity

  • community and familiarity

  • programming depth over production scale

  • nights that feel specific rather than interchangeable

The goal isn’t to create a moment for a camera, it’s to create a night people remember. Importantly, they remember the night (or day; I haven’t forgotten about you, daylife operators and programmers) because they were present in it, not documenting it.

Operationally, Scene Nightlife tends to mean:

  • programming-driven differentiation

  • slower growth but deeper loyalty

  • lower hype volatility

  • stronger long-term cultural positioning

The energy isn’t just explosive, it’s sticky.

Why This Split is Happening: Sameness Fatigue

Guests aren’t just more price-sensitive, they’ve become experience-sensitive.

This has been true for several years now. A significant percentage of consumers make it clear they’re more interested in paying for experience than just buying things.

When nightlife starts to feel like the same playlist in the same room with the same crowd posting the same photos and videos, people pull back. They’re not rejecting nightlife entirely but they see no value in buying into interchangeable nights.

Spectacle formats that don’t evolve quickly enough collapse into noise. Scene formats, when done well, stand out because they feel specific to a sound, a community, a neighborhood, a subculture.

This is the backdrop against which Canada’s nightlife markets are operating.

How Canada’s Markets Reflect the Split

Vancouver: The Rise of the Intentional Night

Vancouver behaves increasingly like a Scene-leaning market.

Instead of broad, mainstream club ecosystems, the traction is in curated parties, themed nights, listening-bar energy, and ticketed or semi-ticketed events.

Discovery often happens through community networks, not just mass promotion. Nights with a clear identity (sonic, cultural, or thematic) outperform generic formats.

Operator lesson: Vancouver rewards clarity over scale. Being for someone beats trying to be for everyone.

Toronto: Big Enough for Both, Brutal to the Weak

Toronto can support Spectacle Nightlife. It has the population, tourism flow, and density to sustain high-visibility formats.

However, Toronto also punishes mediocrity, and it does so quickly.

At the same time, Toronto’s neighborhood ecosystems and niche venues show strong Scene dynamics. There are music-first rooms, culturally anchored spaces, and smaller venues with loyal followings.

Operator lesson: Toronto isn’t anti-spectacle, it’s anti-average. If you’re running Spectacle logic, it has to be sharp. On the other hand, if you’re Scene-driven, it has to be real.

Calgary: Social Infrastructure Over Spectacle

Calgary leans naturally toward Scene Nightlife.

The strength of its after-dark culture often lives in live music, approachable social bars, neighborhood movement, and nights built around connection, not performance.

This is nightlife as habit, not event. The room is a place to gather, not a place to stage a moment.

Operator lesson: Not every market wants a stage; some just want a room. Concepts that feel like community infrastructure rather than Spectacle venues hold traction.

Montreal: Culture as Competitive Advantage

Montreal’s nightlife behaves most like culture, not just entertainment.

Its advantage isn’t just venue count, it’s in neighborhood identity, programming depth, and scenes with history and credibility.

Even when venues scale, they often retain a Scene backbone: a sense that guests are stepping into a space that has context and character.

Operator lesson: You can’t manufacture Montreal-style nightlife with capital alone. Culture compounds, but only if it’s protected.

What This Means for Operators

The biggest mistake right now is trying to sit in the middle. Borrowing the look of Spectacle Nightlife without the engine or trying to co-opt the vibe of Scene Nightlife without the depth are failing “strategies.”

Positioning Question: Which model are you building?

This choice shapes a number of crucial operating elements, such as:

  • marketing strategy

  • staffing profile

  • programming cadence

  • revenue rhythm

  • risk tolerance

If You’re Spectacle-Leaning:

You need a strong visual and production identity, constant programming evolution, social momentum, and a content strategy.

Further, you’ll need to maintain operational precision under pressure.

If you choose to operate in the space of Spectacle Nightlife, you’re in the attention business; stagnation is your enemy.

If You’re Scene-Leaning:

You need consistent, credible programming. You’ll also need to build a team who understands culture, not just service.

Scene Nightlife operators must commit to community integration. Community in the sense of the immediate neighborhood, the town or city, and the subcultures targeted in the programming.

Crucially, if you’re a Scene Nightlife operator, you’ll need patience. Your brand will build more slowly but will also last longer.

You’re in the belonging business, and authenticity is your currency.

The New Competitive Advantage

Neither Spectacle nor Scene Nightlife concepts can rely on buildout alone for an advantage. Similarly, they can’t rely on table and bottle sales, nor will they succeed simply because of their talent bookings.

The new, clear competitive advantage in nightlife, regardless of how the concept leans, is clarity of experience design. Clarity is what creates gravity, the invisible force that pulls the right guests back, again and again.

Nightlife operators need to ask key questions about their experience design and programming:

  • What kind of night is this?

  • Who is this night for?

  • Why should a guest return after this night, not just once but habitually?

The markets that will thrive aren’t the ones with “more nightlife.” They’re the markets with clearer nightlife: concepts that understand whether they’re building spectacle or building scene, and align every decision accordingly.

It’s important to understand that nightlife hasn’t split because guests have stopped going out. The reality is that nightlife has split because because guest attention has changed.

Operators who understand this shift aren’t just surviving this era, they’re the leaders who will define what going out looks like next.

Related Reading

Image: Phat Doan via Pexels

Work with Us

Click the image below to work with KRG Hospitality on your nightlife concept. Cheers!

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Canada’s Emerging Culinary Hubs and Why Strong Ecosystems Matter Now

Canada’s culinary identity isn’t defined by a handful of famous restaurant cities, but by a nationwide shift toward chef-driven regional expression.

These are culinary hubs where local ingredients, immigrant influence, and cultural revival are turning entire neighborhoods and secondary markets into the country’s next great dining destinations.

For years, conversations about Canadian dining have centered on a few obvious cities. However, that myopic view misses the real story unfolding across the country.

What’s happening now isn’t just growth, it’s decentralization. Chefs are leaning into regional identity, immigrant culinary traditions are shaping modern menus, Indigenous and heritage cuisines are experiencing a resurgence, and smaller markets are building serious food credibility.

The result? Canada’s culinary gravity is spreading outward, neighborhood by neighborhood, province by province. It’s creating a network of emerging hubs that operators, investors, and food travelers alike should be watching closely. Established culinary hubs are positioned for even more growth, and new, exciting destinations are poised for their time to shine.

Canada’s most exciting food scenes are no longer limited to major cities. Chef-driven regional cuisine and culturally rooted neighborhoods across every province are creating the country’s next wave of culinary destinations.

While this is exciting, it reveals a stark truth: closures will also reshape Canada’s culinary markets. Survival won’t be random.

The areas most likely to endure are those with strong culinary identity, independent operator density, regional ingredient stories, and genuine destination pull. These are ecosystems that tend to consolidate rather than collapse. This makes them particularly valuable ground for operators selecting a location to start their first concept, those working to stabilize operations, and for brands preparing to scale, offering a more resilient foundation than generic commercial strips.

by David Klemt

A close-up view of the gourmet plating of proteins, taken in Toronto, Canada

Ontario

How best to boil down Ontario’s rich culinary scene? If I had to pick just a few accurate descriptors, I’d say it’s chef-driven, globally-inspired, and diverse, and that last one may be an understatement.

It’s also undeniable that the farm-to-table movement has taken hold throughout the province.

Watch Riverside/Leslieville in Toronto, where independent, chef-driven concepts continue to cluster east of the core, and Prince Edward County, which is evolving from wine-country getaway into a year-round culinary destination. Also, monitor Ottawa’s Wellington West corridor, where neighborhood-scale dining energy keeps building beyond ByWard’s traditional gravity.

Toronto

Top Culinary Hubs

  • Chinatown
  • The Danforth
  • Gerrard East
  • Kensington Market
  • Koreatown
  • Queen West

Ottawa

Top Culinary Hubs

  • ByWard Market
  • Elgin Street
  • The Glebe
  • Little Italy
  • Wellington West

Québec

Anyone looking for rich and indulgent dining experiences will be rewarded in Québec. Smoked meats, duck, pork, wild game, incredible cheese production, a focus on charcuterie and pâtisserie, and a vibrant maple syrup culture all define the province’s approach to cuisine.

Rather than focusing on broad, already-established neighborhoods, watch micro-corridors within Montréal’s Mile End and Plateau. These areas are where new independent kitchens are pushing modern Québécois and immigrant-influenced cuisine forward.

In Québec City, Saint-Sauveur and the expanding Saint-Roch fringe show the strongest signs of becoming the city’s next chef-driven growth zones.

Québec City

Top Culinary Hubs

  • Grande-Allée
  • The Island of Orléans
  • Limoilou
  • The Old Port
  • The Petit Champlain District
  • Saint-Roch

Montréal

Top Culinary Hubs

  • Atwater Market
  • Chinatown
  • Downtown
  • Le Central
  • Little Italy
  • Mile End
  • Old Montreal
  • Plateau
  • Time Out Market

British Columbia

Anyone who has spent time diving into BC’s culinary scene knows a few things to be true: the food is clean and captures the Pacific’s terroir, the province’s chefs are masters of seasonal fare, several Asian cuisines are well represented, and seafood and wine are shine.

Kelowna is solidifying itself as BC’s most complete emerging culinary city, where wine, agriculture, and chef ambition intersect. Kamloops is building quiet momentum through event-driven food culture and local-forward dining. Within Vancouver, watch continued restaurant density growth in Mount Pleasant and the Commercial Drive area, where neighborhood dining culture is deepening.

Vancouver

Top Culinary Hubs

  • Chinatown
  • Gastown
  • Granville Island
  • Kitsilano
  • Richmond
  • The West End

Victoria

Top Culinary Hubs

  • Downtown
  • Chinatown
  • Fisherman’s Wharf
  • Inner Harbour
  • James Bay
  • Old Town

Alberta

Where’s the beef? It’s in the finest restaurants across the world, as Alberta’s known for its ranches and super-premium beef. Of course, there’s also elk, bison, and incredible wild game.

The province is largely renowned for its rustic cooking, bold flavors, and growing craft beer and spirits scenes.

In Edmonton, keep an eye on the Jasper Avenue corridor and adjacent downtown-adjacent districts, where revitalization and restaurant clustering are aligning. In the Rockies, Canmore is steadily transitioning from tourist stop to serious dining town, with chef-led concepts raising the ceiling on expectations.

Calgary

Top Culinary Hubs

  • 17th Avenue SW
  • Downtown
  • Eau Claire
  • Inglewood
  • Kensington

Edmonton

Top Culinary Hubs

  • 104th Street
  • 124th Street
  • Brewery District
  • Downtown
  • Garneau
  • Glenora
  • Mill Creek
  • Old Strathcona
  • Ritchie
  • Wîhkwêntôwin (formerly Oliver)

Manitoba

The province is known for freshwater treasures like Lake Winnipeg pickerel, along with cuisine influenced by immigrant comfort foods. Of note, Ukrainian, Mennonite, and Eastern European dishes.

Manitoba is also making a name for itself through foraged foods and wild rice.

Beyond Winnipeg’s established districts, Corydon Village continues to evolve into a more chef-driven dining strip, while Wolseley shows signs of strengthening as a neighborhood-scale food destination built around independent operators rather than chains.

Winnipeg

Top Culinary Hubs

  • Downtown
  • Exchange District
  • The Forks
  • Red River
  • Sports, Hospitality and Entertainment District (SHED)
  • Waterfront

Brandon

Top Culinary Hubs

  • Downtown
  • 18th Street Corridor
  • West End

Saskatchewan

New Prairie cuisine is a chef-driven movement putting modern spins on traditional dishes. In Saskatchewan, the province’s status as an agricultural powerhouse helps this movement shine. Saskatchewan is also experiencing an indigenous culinary revival.

Riversdale in Saskatoon is evolving from up-and-coming to culinary identity district, driven by independent restaurants and walkable density. In Regina, the Warehouse District continues to position itself as the city’s most concentrated food-and-nightlife corridor.

Saskatoon

Top Culinary Hubs

  • Briarwood
  • City Park
  • Downtown
  • Nutana
  • Stonebridge

Regina

Top Culinary Hubs

  • Albert Street
  • Cathedral Village
  • Downtown

Nova Scotia

Given its status as “the Seafood Capital of Canada,” driven in part by the billions in seafood the province exports to dozens of countries, it’s tough to beat Nova Scotia’s maritime-focused food scene. While there are rustic bites, there’s pride in Nova Scotia in producing elegant and refined dishes.

The Annapolis Valley (in particular, Wolfville) is becoming a true food-and-wine ecosystem rather than just a scenic stop, with agriculture, vineyards, and ambitious chefs converging into destination dining appeal.

Halifax

Top Culinary Hubs

  • Agricola Street
  • Argyle Street
  • Downtown
  • Halifax Seaport Farmer’s Market
  • The Halifax Waterfront

New Brunswick

A coastal powerhouse, New Brunswick will give any coastal location a run for its culinary money. Just consider that Shediac is referred to as “the Lobster Capital of the World,” and Cap-Pelé is considered by many to be “the Smoked Herring Capital of the World.”

And those are but two examples of New Brunswick’s incredible seafood. It’s undeniable that the province’s vibrant Acadian culture has influenced New Brunswick’s maritime mastery and rich food scene.

In Moncton, watch downtown-adjacent corridors near the core rather than any single street; restaurant growth is spreading outward. Coastal communities like Cap-Pelé and Shediac will continue gaining attention as regional seafood identity centers rather than purely seasonal stops.

Fredericton

Top Culinary Hubs

  • Downtown
  • Historic Garriston District
  • Northside

Moncton

Top Culinary Hubs

  • Downtown
  • St. George Street
  • West End

Newfoundland & Labrador

If rustic, heritage-driven cuisine is what someone craves, this province’s chefs deliver. Newfoundland & Labrador’s culinary scenes are rich with both traditional and modern takes on comforting, nostalgic dishes, and chef-driven concepts are modernizing dining options throughout the province.

The Bonavista Peninsula (including Bonavista and nearby coastal communities) is developing into a recognized culinary subregion, where chef-driven coastal gastronomy and heritage cooking are drawing national attention.

St. John’s

Top Culinary Hubs

  • Downtown
  • Duckworth Street
  • Quidi Vidi Village
  • Pleasantville
  • St. John’s Farmer’s Market
  • Water Street

Prince Edward Island

It may be the smallest province but Prince Edward Island boasts super-clean ingredients, be they in the form of seafood or its agricultural bounty. PEI delivers huge flavor and pristine bites.

Beyond Charlottetown, Rustico and Brackley Beach show the strongest signs of developing into seasonal micro-hubs built around seafood, agriculture, and destination-focused dining. These may be smaller in scale, but they’re high in culinary quality.

Charlottetown

Top Culinary Hubs

  • Downtown
  • Richmond Street
  • Victoria Row
  • Waterfront
  • West Royalty

Outside of Charlottetown

  • New Glasgow
  • New London
  • Summerside
  • Victoria-by-the-Sea

Image: Javon Swaby via Pexels

Along with other sources, the author reviewed the Destination Canada website for information.

Related Reading

Work with Us

Click the image below to work with us on starting, stabilizing, or scaling your hospitality concept.

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

WalletHub Ranks the Best Foodie Cities in the US for 2026

Personal finance and financial education company WalletHub has ranked the top 182 foodie cities in the USA for the year 2026.

Several metrics were considered, scored under two primary dimensions, Affordability, and Diversity, Accessibility & Quality. These include:

  • Accessibility & Affordability of High-Quality Restaurants
  • Restaurant Meal Cost
  • Average Beer & Wine Price
  • Restaurants per Capita
  • Ratio of Full-Service Restaurants to Fast-Food Establishments
  • Growth in Number of Full Service Restaurants

The company has been releasing this list since 2014, and released their latest ranking at the end of September of last year. Their rankings give operators several considerations for starting, stabilizing, or scaling their concepts in 2026 (and beyond).

For example, will their concept face stiff competition in a particular city due to market saturation, or will it stand out because it fills a gap? Will a market’s economics, demographics, and pyschographics support an operator’s expansion, or would it perform far better elsewhere? Just these two questions highlight the importance of a feasibility study, among other fact-based approaches and considerations.

When they first started, WalletHub ranked 150 cities. That expanded to more than 180 quite quickly.

This year’s number-one city also earned the top spot on the 2024 list. Scroll down to check out the latest ranking of American foodie cities. Cheers!

by David Klemt

Ocean Drive in South Beach, Miami, Florida, during the daytime

Hint for the city that earned the top spot.

America’s Top Foodie Cities

The Top 25

  1. Miami, Florida
  2. Portland, Oregon
  3. San Francisco, California
  4. Seattle, Washington
  5. Orlando, Florida (#1: Most Ice Cream & Frozen Yogurt Shops per Capita)
  6. Austin, Texas
  7. Tampa, Florida
  8. Las Vegas, Nevada (#1: Most Restaurants per Capita)
  9. Sacramento, California
  10. San Diego, California
  11. Atlanta, Georgia
  12. Denver, Colorado
  13. Pittsburgh, Pennsylvania
  14. St. Louis, Missouri (#1: Most Gourmet Specialty-Food Stores per Capita)
  15. Houston, Texas
  16. Los Angeles, California
  17. Milwaukee, Wisconsin
  18. Richmond, Virginia
  19. Cincinnati, Ohio
  20. Washington, DC
  21. Fort Lauderdale, Florida
  22. San Antonio, Texas
  23. Chicago, Illinois
  24. Grand Rapids, Michigan
  25. Dallas, Texas

26 to 50

  1. New York, New York
  2. Wilmington, Delaware
  3. Oakland, California
  4. Louisville, Kentucky
  5. Phoenix, Arizona
  6. Scottsdale, Arizona
  7. Philadelphia, Pennsylvania
  8. Salt Lake City, Utah (#1: Most Coffee Shops per Capita)
  9. Buffalo, New York
  10. Portland, Maine
  11. Long Beach, California
  12. Omaha, Nebraska
  13. Anaheim, California
  14. San Jose, California
  15. Minneapolis, Minnesota
  16. Nashville, Tennessee
  17. Vancouver, Washington
  18. Raleigh, North Carolina
  19. Rochester, New York
  20. Charlotte, North Carolina (tie)
  21. Cleveland, Ohio (tie)
  22. Madison, Wisconsin
  23. Aurora, Colorado
  24. Indianapolis, Indiana
  25. Baltimore, Maryland

51 to 75

  1. Fresno, California
  2. Boston, Massachusetts
  3. Providence, Rhode Island
  4. Tucson, Arizona
  5. Tulsa, Oklahoma
  6. El Paso, Texas
  7. Honolulu, Hawaii
  8. Bakersfield, California
  9. Reno, Nevada (#1: Lowest Average Beer & Wine Price)
  10. Albuquerque, New Mexico
  11. Springfield, Missouri
  12. Stockton, California
  13. Virginia Beach, Virginia
  14. Santa Ana, California
  15. Charleston, South California
  16. Santa Rosa, California (#1: Most Craft Breweries & Wineries per Capita)
  17. Colorado Springs, Colorado
  18. Spokane, Washington
  19. Jersey City, New Jersey
  20. Columbia, South Carolina
  21. Greensboro, North Carolina
  22. St. Petersburg, Florida
  23. Dover, Delaware
  24. Columbus, Ohio
  25. Newark, New Jersey

76 to 100

  1. Tempe, Arizona
  2. Jacksonville, Florida
  3. New Orleans, Louisiana
  4. Tacoma, Washington
  5. Modesto, California
  6. Detroit, Michigan
  7. Oklahoma City, Oklahoma
  8. Salem, Oregon
  9. Knoxville, Tennessee
  10. St. Paul, Minneapolis
  11. Billings, Montana
  12. Amarillo, Texas
  13. Plano, Texas
  14. Fort Worth, Texas
  15. Tallahassee, Florida
  16. Manchester, New Hampshire
  17. Warwick, Rhode Island
  18. Missoula, Montana
  19. Wichita, Kansas
  20. Sioux Falls, South Dakota
  21. Burlington, Vermont
  22. Cedar Rapids, Iowa
  23. Lincoln, Nebraska
  24. Durham, North Carolina
  25. Des Moines, Iowa

To check out cities 101 through 180 and learn more about WalletHub’s methodology, click here.

173 to 182

The following cities complete the list, earning the final ten slots on the list.

  1. Columbus, Ohio
  2. Yonkers, New York
  3. Rancho Cucamonga, California
  4. Shreveport, Louisiana
  5. West Valley City, Utah
  6. Jackson, Mississippi
  7. Montgomery, Alabama
  8. Moreno Valley, California
  9. Lewiston, Maine
  10. Pearl City, Hawaii

Top 10 Foodie Cities in the US (2024)

The top ten foodie cities heading into last year are listed below.

  1. Miami, Florida
  2. San Francisco, California
  3. Orlando, Florida
  4. Portland, Oregon
  5. Tampa, Florida
  6. Sacramento, California
  7. Las Vegas, Nevada
  8. Seattle, Washington
  9. Denver, Colorado
  10. San Diego, California

Top 10 Foodie Cities in the US (2014)

For those who are curious, WalletHub’s first list, published in 2014, is below. For their inaugural list, the company ranked 150 cities.

Things have certainly shifted over the course of more than a decade.

  1. Orlando, Florida
  2. Grand Rapids, Michigan
  3. Madison, Wisconsin
  4. Boise, Idaho
  5. Cincinnati, Ohio
  6. Reno, Nevada
  7. New Orleans, Louisiana
  8. Austin, Texas
  9. Lexington, Kentucky
  10. Pittsburgh, Pennsylvania

Henderson, Nevada, was ranked 150.

Image: Luise and Nic on Unsplash

Related Reading

Work with Us

Click the image below to work with us on starting, stabilizing, or scaling your F&B or hospitality concept.

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

2026: Animals vs. Plants?

2026: Animals vs. Plants?

by David Klemt

Fine-dining plating of beef at a gourmet dining experience in Alberta, Canada

Gourmet dining experience featuring Canadian beef.

According to Datassential, plant-based meat and seafood alternatives have reached a plateau, meaning that animal meats should go hard in 2026.

Last September, the F&B intelligence platform surveyed 993 consumers who eat both animal and plant-based meats. Most indicated that they were more interested in the former than the latter.

There are three primary factors driving this sentiment, per Datassential. The top factor is how natural one category is in comparison to the other. Second is versatility. And third, which is perhaps the most important to operators with food programs, is craveability.

More Natural

Of the 993 survey respondents, 65 percent indicated that animal meat is more natural to consume than its plant-based counterparts. This appears to be the top concern or motivating factor, as it represents the greatest sentiment per respondents.

This does make some sense, at least to me. Over the past several years I’ve heard variations of this point of view at restaurants, inside kitchens, in discussions with F&B peers, while speaking with clients, and at trade shows. A common misgiving can be summed up thusly: “We don’t know exactly what they’re putting in these products.”

That doesn’t bode well for overall consumer perception.

More Versatile

Survey respondents also expressed that they feel animal meats are more versatile than plant-based alternatives. In fact, 61 percent shared that opinion.

Again, I’ve heard variations of this statement several times, and I’m sure I’m not the only one. You’ll hear “But what do I do with it?” at trade shows where there are plant-based brands exhibiting at booths and doing demos.

More Craveable

Finally, craveability. This is an interesting one. Nearly 60 percent of respondents (59%) stated that they crave animal meat on a regular basis. On its own, that’s not an incredible stat. However, that majority opinion consists of people who don’t follow through on that craving.

In other words, even people who don’t eat animal meat regularly feel its pull. That doesn’t necessarily include people who adhere to vegetarian or vegan diets, but it’s possible.

More Meat

Along with this comes some insight into consumption habits. Per the Datassential survey, 37 percent of respondents increased their consumption of animal meat more than they boosted their intake of plant-based counterparts.

This is logical when we take the three sentiments above into account as a whole. If something is more natural, more versatile, and more craveable, it stands to reason consumers are going to choose to consume it, and even consume more of it more often.

It’s also possible this increase relates to consumer interest in proteinmaxxing.

More Choices

So, where does this leave operators and their food programs?

Well, it leaves them needing to make programming, menu, and inventory choices.

Datassential suggests that plant-based meats have plateaued in the retail space. It certainly seems that consumer sentiment toward plant-based meats has also plateaued among consumers, based on their survey results.

However, that doesn’t mean operators should abandon plant-based meats and altogether. The better, more intentional approach is to run reports, analyze the data, and make choices with surgical, informed precision.

What do the numbers indicate? Are plant-based meats lagging, and are they taking up valuable inventory space? If orders for plant-based meats are declining, what do sales for “center-of-plate” vegetables look like? What can be leaned into harder, what can be adjusted, and what should be removed?

And, crucially: Are the choices for moving forward being made in a well-considered, intentional manner, or are they just knee-jerk reactions and guesses?

It’s worth noting that Datassential’s consumer sentiment survey focuses on plant-based meats, not just plants. The survey respondents didn’t indicate a decline in interest for items like cauliflower or portobello steaks.

Whatever choices are made, operators need to leverage data and facts, and follow the Three Ps: People, Processes, and Profits.

Image: Deane Bayas via Pexels

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Tequila may Drive These 2026 Trends

Tequila may Drive These 2026 Trends

by David Klemt

Clear glasses filled with tea, served from a silver teapot at a restaurant

Is there alcohol in that teapot? Maybe.

While some of us continue to cross our fingers that tequila will have their year as the top spirit, other similar sips may rise up in 2026.

One can argue that tequila finally clinched the Top Spirit crown in the US and made 2025 its year. After all, it showed the fastest growth of any spirit last year.

Further, some sources report that tequila generated more revenue than any other major category in the US. Per reporting, premiumization is believed to be a major driver of tequila’s 2025 success.

However, other sources report that vodka still holds the throne due to volume sales. It probably won’t shock a single person that Tito’s holds the number one spot as 2025’s top-selling brand.

In Canada, beer earned the top spot by overall market share. However, Canadian whisky led in 2025 as the top spirit, though tequila garnered notable interest.

Meanwhile, two spirits similar to tequila may finally have meaningful moments in 2026 as vodka and the world’s most-famous agave spirit battle for the title. If Datassential and Nation’s Restaurant News are accurate in their predictions, raicilla and sotol may finally become even more well known to consumers this year.

What is Raicilla?

This agave spirit has been produced in Jalisco, Mexico (for the most part), for at least three centuries. And yet, it wasn’t granted its own Denominación de Origen (Designation of Origin, or DO) until 2019.

Authentic raicilla can only be produced in 16 municipalities throughout Jalisco, and, for some reason, one municipality in Nyarit, called Bahía de Banderas.

There are essentially two regional types of raicilla, de la costa and de la sierra. As the names imply, the former are coastal raicillas, and the latter are from mountainous areas.

Some varieties of raicilla will be familiar to tequila drinkers: joven, reposado, and añejo. There are also varieties that have been aged or matured in glass, abocado (infused raicilla), and artisanal double-distilled raicilla.

Unlike tequila, which can only be made from Blue Weber agave, raicilla is made from several different types of agave. Intriguingly, most raicilla is made with wild agave. The reason is simple: raicilla production is nowhere near the scale of tequila, so for the most part, producers don’t need to cultivate huge fields of agave.

Generally speaking, there are two primary approaches to cooking agave for raicilla, resulting in different flavor profiles. De la sierra producers tend to cook the agave above ground. Conversely, de la costa producers mainly utilize underground or pit ovens.

So, de la sierra raicilla usually doesn’t have smoky notes like mezcal, whereas de la costa raicilla is more likely to share that profile. Generalizing again, raicilla is characterized most often as being more floral and vegetal than tequila and mezcal. Really, a raicilla’s flavors and aromas are highly dependent on terroir.

What is Sotol?

Contrary to a common misunderstanding, sotol isn’t derived from agave. One common thread connecting tequila and sotol is the fact that they’re both traditional Mexican distilled spirits.

Another similarity is the production method: piñas are harvested and cooked, then fermented and distilled.

However, it’s a plant known as Dasylirion that’s used to produce sotol. Commonly known as “desert spoon,” this plant is a member of the asparagus family, as is agave. This may be what leads some to believe that sotol and tequila are both agave-based spirits.

Like tequila and raicilla, sotol is protected by a DO. This means true sotol can be produced exclusively in the Mexican states of Chihuahua, Coahuila, and Durango. It must be noted, though, that there are producers in Texas “don’t recognize” the DO and bottle what they call sotol.

A detail that may appeal to more sustainability-minded guests: sotol production is considered more eco-friendly in comparison to tequila and raicilla. When harvesting desert spoon for sotol, the roots aren’t dug up, meaning a single plant is capable of producing several bottles of sotol over its lifetime.

Desert spoon piñas are cooked in an earthen pit, and terroir is a factor. Depending on the region—desert, forest, or prairie—a sotol will have different flavor and aroma profiles.

For example, a forest sotol may have notes of pine, eucalyptus, and mushroom. In contrast, a desert sotol may be characterized by leather and pepper. Sotol is complex and will keep the adventurous engaged for quite some time.

How can Operators Capitalize?

One of the most effective ways to introduce guests to raicilla and sotol is to leverage the undeniable and seemingly unstoppable popularity of tequila.

And while it’s fun to nerd out over production, it’s likely a better idea, initially, to taste guests on tequila, raicilla, and sotol. While you’re there, you can also include mezcal.

Particularly notable is NRN itself predicting sotol as a trend of its own this year. Further, Datassential has identified raicilla as a trend in their own report.

Of course, there are also some compelling 2026 trend predictions you can leverage with these two traditional Mexican spirits.

Both raicilla and sotol are more than capable of standing in for tequila and mezcal in cocktails. However, raicilla can also tag in for gin, and sotol can act as substitute for gin and vodka.

Off the top of my head, raicilla or sotol Margaritas and Negronis should appeal to a wide range of guests.

This brings me to a simple trend that NRN predicts may take off in 2026: smaller cocktails.

Think (and Price) Small

That’s it; it’s that simple. People seem to be drinking less, not just in frequency but in ABV.

So, it may behoove operators to offer smaller cocktails, accompanied by appropriately reduced prices. This means the drinks are priced appropriately rather than offering discounts in the hopes of driving traffic.

Not only does this move, when intentional, speak to a current shift in guest imbibing behavior, and appeals to those who want to go out to bars and restaurants but don’t want to spend much.

The New Happy Hour

This is where a few trends converge. According to Datassential, “teatime is the new happy hour.”

And per The IWSR, playfulness may also take hold in 2026. I’m sure you can see where this is going.

In Datassential’s view, teatime rather than traditional happy hour gives operators more leeway in terms of dayparts. Noon, early afternoon, early evening, brunch… It’s all on the table, and there isn’t confusion around start and stop because it’s not referred to as a happy hour.

It also allows operators to offer tea-based cocktails made with raicilla and sotol (or any other spirit), and low- and no-ABV tea drinks. Again, this speaks to a range of consumer behaviors and expectations.

The Three Ps

Whatever trends operators choose to pursue this year, their decisions must be intentional.

That means viewing them through the lenses of People, Processes, and Profits.

People: Do we have the right people in place in the right roles? Are we serving our guests to the best of our abilities? Team member or guest, are we truly treating everyone with respect and gratitude?

Processes: How often are we reviewing each operational element? Are we reviewing our menus at regular intervals over the course of 12 months, or are we doing this annually (or not at all)? How are we approaching our pricing? When was the last time we reviewed and tested each and every one of our systems?

Profits: Total sales are great, but are we making money? As Doug Radkey, president and principal consultant of KRG Hospitality says, “Sales are a vanity metric. Profits tell the real story.” Do we know our numbers? Are we controlling costs? Do we make pricing and labor decisions proactively and strategically, or are we panicking and reacting without careful consideration?

Those are by no means all of the questions we need to ask on a regular basis, but they’ll give operators a solid baseline.

Image: Davey Gravy via Unsplash

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Is 2026 the Year of ‘Maxxing?

Is 2026 the Year of ‘Maxxing?

by David Klemt

Stark image of a speed limit sign that reads "MAXIMUM 30"

If we pretend this is referring to grams of fiber, that’s excellent fibermaxxing.

If recent reports and consumer behaviors are any indication, and I think they are, health-conscious “maxxing” trends are on the menu in 2026.

Currently, proteinmaxxing appears to be king of Diet Trend Hill.

In 2026, though, protein may face a realistic contender for the crown: fiber.

Look it up and you’ll see it’s not an entirely new trend, and has been on the upswing since at least the middle of 2025.

For operators, this is yet another consumer signal. The interest (some would say obsession) in high-protein diets has inspired menu changes across categories. Whether a QSR with global reach, a regional chain, or a local independent, restaurants have been responding to their guests’ desire to consume more protein.

Now, it’s possible an interest in a high-fiber diet may inspire more menu changes and additions.

What is GLP-1?

Would you like a healthy dose of pedantry? Fantastic.

“GLP-1” stands for “glucagon-like peptide 1,” which is a hormone found in our bodies. When we eat something, GLP-1 stimulates insulin secretion.

A GLP-1 drug is an “agonist.” That is, it mimics, in this case, a hormone to cause a response.

So, when we talk about GLP-1, it’s a hormone; when we talk about the drug, it’s a substance humans take predominantly via injection. Pedantry: complete.

It may seem as though these drugs came onto the market just before Covid ravaged the world. However, the hormone was discovered around 50 years ago, and the first GLP-1 medication was approved by the FDA just over 20 years back to treat type 2 diabetes. From 2018 to 2023, according to multiple analytics sources, interest in, and use of, GLP-1 drugs for weight loss exploded.

GLP-1 medications cause the body to delay emptying the stomach. Further, the drugs tell the brain to reduce the desire to eat. Both actions curb appetite, and tend to result in significant weight loss.

Of course, side effects have been reported widely. Those who experience rapid weight loss may experience “Ozempic face.” According to Harvard Health Publishing (2004), this appearance is characterized by:

  • a hollowed look to the face
  • changes in the size of the lips, cheeks, and chin
  • wrinkles on the face
  • sunken eyes
  • sagging jowls around the jaw and neck.

There are also several gastrointestinal side effects one can experience, but I’ll let you use your imagination rather than list them.

What is Proteinmaxxing?

This one is quite a bit simpler to understand: It’s focusing on the consumption of protein, and “maxxing” it out. I assume there are two Xs to really drive home the point that something is being maximized.

Taken to the max (or “maxx,” I guess), there are proteinmaxxers who aim to consume 200 grams of protein per day. According to Cargill, a company that distributes high-protein products, there are “entire ‘social subcultures'” built around the consumption of high-protein diets. Essentially, for some proteinmaxxers, the diet is more like an ideology.

However, some doctors believe consuming that much protein can be harmful, not healthy.

Recognizing that there’s a range when it comes to protein consumption (age, activity level, etc.), there are some general guidelines one can follow.

Using the standard 2,000-calorie-per-day diet, common guidance is that 10 to 35 percent of calories should come from protein. For an “average” person, daily protein consumption can be calculated at 0.8 grams per kilogram of body weight. So, someone who weighs 150 pounds (68 kilograms) should consume 54 grams of protein per day.

People tend to face muscle loss in their 40s or 50s, and therefore should aim for 1.0 to 1.2 grams of protein per kilogram of body weight. On the high end, for that hypothetical person weighing 150 pounds, that’s an increase to 82 grams of protein.

Those who exercise regularly should increase protein consumption to 1.1 to 1.5 grams; that rises to 1.2 to 1.7 grams for people who lift weights or do other strenuous exercise on a regular basis. Using the high end, that’s 102 grams of protein per day for the former, and 115 to 116 grams for the latter.

Consuming 2.0 grams of protein per kilogram of body weight is considered “excessive” by some.

What is Fibermaxxing?

If you’re guessing that fibermaxxing is similar to proteinmaxxing, you’ve nailed it.

That said, the numbers are absolutely not the same in comparison to proteinmaxxing.

Unless something changes, the current definition of fibermaxxing appears to fall in line with current dietary recommendations: 25 to 38 grams of fiber per day.

Going deeper, nutrition guidelines state that the source of fiber should be food rather than supplements.

However, most Americans and Canadians consume just 14 to 15 grams of fiber per day. That’s a shortfall of 10 to 11 grams, every day.

It must be noted, however, that some people need to adhere to low-fiber diets for medical reasons. Further, while there’s some debate, some believe 50 grams of fiber is excessive; others feel that too much fiber is closer to 70 grams per day.

How does excessive fiber intake manifest? Again, that’s largely gastrointestinal, and, again, I’ll leave that to your imagination.

That’s all to say this: proceed with caution when trying out any diet, and try to find what’s best for you and your body.

Like protein, fiber can aid in weight loss. So, with the rise of GLP-1 medications, it’s unsurprising that some people trying to lose weight are focused on fiber while some have lasered in on protein.

What is the Point?

“David… Seriously, what the hell? Thanks for the dietary info, but what are we doing here?” I can hear some of you asking.

Simply put, operators need to be aware of large-scale consumer trends. They must consider how it can affect their people, processes, and profits.

Per Datassential, just 13 percent of operators are aware of fibermaxxing.

Borrowing from Datassential’s trend ranking system (Inception, Adoption, Proliferation, and Ubiquity), it’s fair to say fibermaxxing consumers are either on the cusp of moving on from inception to adoption or are already there.

As far as proteinmaxxing, that’s definitely in proliferation territory. What’s my evidence? A QSR, Arby’s, to be precise, introduced Steak Nuggets in Q4 of 2025. That’s an entirely different spin on nuggets in fast food, and even if it’s not stated explicitly, that certainly appears to be an appeal to proteinmaxxers looking for a snack.

There’s also the seeming addition or infusion of protein to all manner of food and drink items on menus across all categories of restaurants.

Protein-infused coffee drinks, protein-enhanced pastries, QSR meal combos for people leading a high-protein lifestyle… There are lists online of the top orders at various chains for consumers seeking protein. Of course, there are also lists online identifying high-fiber items offered by various well-known restaurants.

Then we can look to retail labeling. Unsurprisingly, food brands want to leverage increased consumer interest in protein, fiber, and other nutritional values. These companies are calling out their protein and fiber values to encourage purchases and brand loyalty.

Restaurants and bars can do the same. In some cases (more than you many think), a given menu already has high-protein and high-fiber options; it’s just not called out directly.

What is the Takeaway?

As we kick off 2026, let’s change the approach. If you want to appeal to health-conscious guests, tell them exactly what they want to know.

Review your menu, identify what falls in line with various diets, and call out those values or qualities in the descriptions.

Some consumers are proteinmaxxing. Others are fibermaxxing. Somehow, I expect balancemaxxing (maximizing the focus on a balanced diet; did I just coin a phrase?) to take hold in 2026 or 2027.

Similarly, operators need to focus on profitmaxxing for the financial health of their business, the financial stability of their hardworking teams, and longevity in serving their communities.

It all comes down to the Three Ps: People, Processes, and Profits. Serve the people (including your team members) and perfect your processes, thereby maxxing your profits.

Image: Erik Mclean via Pexels

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Bar Hacks 2025: Top Episodes

Bar Hacks 2025: Top Episodes

by David Klemt

Bar Hacks Spotify for Creators Wrapped 2025 cover

Thank you to every one of our incredible guests and our amazing audience for listening to Bar Hacks and Bar Hacks: ReFire this year!

Season six, which spanned 2025, was another fantastic year for insightful and fun conversations.

Among our informative and engaging guests were Hayden Lambert, who shared his “simplexity” philosophy. Michael Suomi, the creative mind behind several award-winning designs, dropped by for a great chat.

Matty Rangel popped in to chat tending bar, dive and neighborhood bars, crafting engaging content, and more. KRG Hospitality design partner Nancy Kuemper of Mabel Design Co. shared her journey in hospitality design, and her tips for maximizing the client-designer relationship.

Bar Hacks host David Klemt addressed real-world hospitality business situations with Bradley Knebel over the course of several Bar Hacks: ReFire episodes.

Of course, that’s just a handful of the guests and topics from 2025. We’re grateful for everyone who takes the time to stop by and chat with us, and for everyone who listens, subscribes, likes, and shares.

Thank you all so much!

Below, the top episodes of 2025. We’ll see you in 2026! Cheers!

Episode 136 with Hayden Lambert

Our number one episode of 2025! Hayden Lambert, co-founder of the unique and award-winning Above Board bar in Melbourne, Australia, pops by for an incredible chat.

When Lambert would explain the reductionist philosophy behind the concept for Above Board to others in the industry, he was told it wouldn’t work. Well, nearly ten years of operation, a few appearances on the World’s 50 Best Bars list, and other accolades later, Above Board continues to prove that its unique approach works.

On this episode of the Bar Hacks podcast, Lamber discusses his journey through hospitality, traveling the world, still being tested as a bartender, “simplexity,” how brands can succeed in a bar without a back bar, the magic that is making guests feel like their experience was easy, and much, much more.

Lambert drops a ton of useful information and experience in this episode that veteran, new, and hopeful bar owners need to hear and consider.

Spotify

Apple Podcasts

Episode 141: Brand Authenticity: Robert Minucci of Talkhouse Encore

On this episode of Bar Hacks, host David Klemt sits down with Rob Minucci, CEO and co-founder of Talkhouse Encore, a premium RTD brand inspired by the legendary dive bar Stephen Talkhouse in the Hamptons. Together, they delve into the story behind the brand’s inception during the pandemic, discussing how Rob’s business partner Ruby Honerkamp (whose family owns the iconic bar), sought to bring the spirit of the Talkhouse to the masses through gluten-free vodka and tequila seltzers. Or, as Rob explains, dive bar classics in RTD form.

Rob shares insights into the challenges of launching a new beverage brand, from navigating distributor relationships to the importance of creating a standout product that resonates with consumers. He emphasizes the significance of authenticity and flavor, particularly for the Gen Z demographic, who are looking for more than just a drink;they want a story and a connection to the brand.

You’ll learn about the strategic decisions that shaped Talkhouse Encore, including its unique approach to market research and branding. Rob explains how they focused on building a strong local presence before considering expansion, ensuring that they meet consumer demands with quality ingredients and an engaging brand narrative.

Spotify

Apple Podcasts

Episode 134 with William Brooks

On this episode, host David Klemt sits down with William Brooks, the Global Brand Ambassador for Tequila Herradura. With a background from Johnson & Wales University and extensive experience in the spirits industry, William shares his fascinating journey from whiskey to agave.

Discover the unique qualities of tequila, as William dispels common myths and misconceptions. He dives into the importance of terroir, the differences between lowland and highland agave, and how these factors influence flavor profiles. The conversation also covers the innovative practices at Tequila Herradura, including sustainability efforts, and the creation of the reposado category.

Plus, William shares his favorite tequila cocktails, perfect food pairings, and tips on how to properly taste tequila (hint: replace the lime). Whether you’re a seasoned agave enthusiast or just starting to explore, this episode is packed with valuable insights and delicious ideas.

Spotify

Apple Podcasts

ReFire: Brilliant Burgers, Sloppy Service & Persnickety Perception

Guest experience drives perception, and perception shapes value. As you may have already learned, perception can be impacted on what may feel trivial to operators and their teams but is incredibly important from guest to guest.

On this episode of Bar Hacks: Refire, David Klemt, partner at KRG Hospitality, and co-host Bradley Knebel of Empowered Hospitality break down a real-world story of two restaurants offering the same menu and pricing, but with vastly different outcomes. One felt like a letdown because of disorganization and sloppy service; the other delivered a memorable experience simply by getting the fundamentals right.

The duo dig into why poor guest experience makes food and drinks taste worse; why discounting without strategy sends the wrong message; and why every detail—from lighting and music volume to greetings and check drop—matters. If your guests don’t feel good about the experience, they won’t feel good about the value. And if they don’t see value, they won’t see a point in returning for more visits.

Tune in to rethink what you’re really selling.

Spotify

Apple Podcasts

Episode 133 with Michael Suomi

Suomi Design Works is an award-winning hotel design studio dedicated to approaching every hospitality project with an exceptional level of creativity. In fact, Michael Suomi, president of the studio, actively seeks out unique, challenging projects.

On this episode of the Bar Hacks podcast, host David Klemt chats with Michael about a number of these extraordinary projects. Further, Michael shares his approach to onboarding clients, building unique teams for exceptional projects, trends he thinks may stand out in 2025 (and which he’d like to see disappear), and more.

Spotify

Apple Podcasts

Episode 139 with Matthew Rangel

We sit down with real-life bartender, actor, and social media creator Matthew Rangel (@therealmattyrangel) an hour before he needed to open one of the three bars at which he works in Wisconsin to talk neighborhood bars, dive bars, mental health, social media, and the Midwest.

For those who haven’t yet come across Matty’s bartending videos, they’re quick, funny, and relatable to anyone who has worked behind the stick, or worked at a bar or restaurant. Matty breaks down his approach to creating his videos, which is a quicker process than most would likely expect. He also explains that people don’t need to buy the most expensive recording gear or spend hours editing to make impactful videos.

Matty also discusses mental health and the hospitality space, in particular bartending. He hosts Mental Health Mondays each week, hoping for people to reach out, share, connect, and work through their struggles.

Spotify

Apple Podcasts

Episode 140 with Finian Sedgwick

Long-time listeners know we love it when previous guests return! On this episode, Finian Sedgwick, chief growth officer at BAXUS, comes back onto the podcast.

Finian and David chat about the growth of BAXUS and the BoozApp, including new features for the peer-to-peer marketplace, popular bottles and spirits categories, and the rabbit hole members can go down when searching for items to purchase and trade. They also talk about bottles that have grabbed Finian’s attention, why he’s bullish on wine, and how alcohol-free cocktail menus are more important than some operators may think.

Speaking of operators, the two also discuss the doom-and-gloom articles blaming Millennials and Gen Z for “killing” or otherwise “ruining” alcohol consumption and sales. Is that really the state of booze, or are people rage-baiting for clicks, and are some operators failing to meet their guests where they are?

Spotify

Apple Podcasts

Episode 130 with Giuseppe Gallo

Giuseppe Gallo has accomplished a lot in his two decades-plus in the hospitality and beverage spaces: he’s a respected vermouth and amaro expert, the winner of the 2014 Spirited Award for Best International Brand Ambassador, an educator and drinks historian, and a bartender’s bartender.

Among other topics, this episode explores the creation of SAVOIA Americano (and ITALICUS). Giuseppe introduces SAVOIA Orancio, an innovative new aperitivo made with natural orange wine. Throughout the conversation, Gallo
emphasizes the importance of bartender insights in shaping successful beverage brands, and the guest experience.

Spotify

Apple Podcasts

ReFire: Bad Behavior & Ridiculous Regulars

Hosts David Klemt and Bradley Knebel tackle two real-life restaurant and bar situations in the first ReFire of 2025.

The two tackle the topic of an operator who’s hesitant to believe it when multiple employees claim a culinary team member is rude, hostile, and abusive…but believes that team member when they make the same accusation against a quiet but hard-working back-of-house peer. Don’t worry – it gets worse!

Then, David and Bradley take a look at a stunning, on-the-spot termination of a bartender who had been in role since day one. The restaurant was busy, the bar was slammed, and the word of a regular got the bartender of five years fired instantly. Something doesn’t add up!

Look, firing someone is never pleasant. However, it’s going to happen. Operators and leadership team members need to have standards in place and communicated clearly, a process for terminations, and the understanding that how they fire people speaks to their credibility and reputation.

Spotify

Apple Podcasts

ReFire: “We’re Having Dinner—You’re Not”

We managed to squeeze three real-world hospitality situations into episode five of ReFire!

On the last episode, David and Bradley talked about guest perception, and how the “little” things can have a big impact. This time, they discuss brand perception, and how quickly a misstep can turn into a catastrophe.

Then, they talk about “skunking,” and how it impacts your team.

Finally, David and Bradley take a look at a restaurant’s new SOPs shared by a team member, and why they’re a problem.

Spotify

Apple Podcasts

Image: Spotify

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Where Americans are Moving

Where Americans are Moving

by David Klemt

An AI-generated image of a highly modified semi-truck and trailer in red, white, and blue livery, with a matching sportbike next to it.

If you’re going to move, move with some style. (AI-generated image. Shocking, I know.)

Migration has always reshaped the American hospitality landscape, and every wave of movement creates new winners, gaps, and demand curves.

The last several years have accelerated that reality.

People aren’t just moving for work anymore. While that’s still definitely happening, people are moving for many other reasons.

Affordability. Opportunity. Lifestyle. Emotional, mental, and physical safety. Sense of community.

Unsurprisingly, when people move, a market’s hospitality scene also changes.

Operators who understand where (and why) population is flowing hold an advantage. They can get a jump on emerging nightlife pockets, establish their brand, fill gaps in experiential demand, and shape the competitive landscape before it’s saturated.

I’ve addressed this topic a couple of times in the past, and I’ll say now what I’ve said then: Proceed with caution. Don’t move into an entirely new (to you and your business) market just because you see it on a list. Do your due diligence, collect data, and make an informed decision.

One source used for this article, the 2025 PODS Moving Trends dataset, gives us compelling insights. It identifies the top 20 move-in (inflow) markets and top 20 move-out (outflow) markets across the US.

Below is a breakdown of the cities Americans appear to be running toward, and the ones they may be running from, along with my thoughts on what this all may mean for operators who want to look toward the near and distant future.

Top 20 U.S. Inflow Cities/Regions (Operator-Focused Table)

Rank Market / Region Key Drivers Hospitality & Nightlife Opportunities
1 Myrtle Beach, SC/Wilmington, NC Cost, coastal lifestyle Strong tourist and transplant mix. Experiential nightlife.
2 Ocala, FL Affordability, space Upside for casual dining, sports bars, and entertainment hybrids.
3 Raleigh, NC Tech growth, livability Elevated cocktail, chef-driven concepts, and late-night growth.
4 Greenville–Spartanburg, SC Manufacturing boom Fast-growing bar scene. Needs mid-tier nightlife.
5 Dallas–Fort Worth, TX Jobs, affordability One of the hottest nightlife expansions in the US.
6 Charlotte, NC Banking/tech migration Strong brunch, rooftop, and upscale/ultra lounge demand.
7 Boise, ID Outdoor lifestyle Craft spirits, brewery culture, and boutique venues.
8 Knoxville, TN Affordability Venue conversions, and approachable F&B concepts.
9 Nashville, TN Cultural magnet Hyper-competitive but high upside for differentiated concepts.
10 Jacksonville, FL Space, weather Large-format nightlife, and beach-driven experiences.
11 Chattanooga, TN Quality of life Cocktail bars, and neighborhood venues.
12 Huntsville, AL STEM growth Upscale casual. Modern nightlife remains underrepresented.
13 Portland, ME Coastal lifestyle Elevated F&B, and small-format high-end bars.
14 Johnson City, TN Rising affordability Mid-market restaurants, and breweries and brewpubs.
15 Spokane, WA Outdoor migration Coffee/café culture. Need for mid-tier nightlife.
16 Atlanta, GA Urban migration High-volume nightlife, and premium dining.
17 Greensboro, NC Cost Local-driven, neighborhood-first hospitality.
18 Asheville, NC Tourism, creativity Craft-forward bars, chef-driven restaurants, and experiential concepts.
19 San Antonio, TX Population boom High-energy nightlife, and experiential, fusion-driven dining.
20 Dover, DE Cost, proximity Community-focused F&B concepts.

Top 20 U.S. Outflow Cities/Regions (Operator-Focused Table)

Rank Market / Region Key Push Factors Hospitality & Nightlife Challenges
1 Los Angeles, CA Cost of living Talent and guests disperse. Local nightlife softening in mid-tier venues.
2 Northern CA (SF Bay) Cost, taxes Dining scene polarizing: very high-end on one end, budget on the other.
3 South Florida (Miami) Cost spike High-end clubs thrive. Aid-market operators squeezed.
4 Long Island, NY Affordability Retention issues, and older venues struggle.
5 San Diego, CA Housing cost Neighborhood bars lose regulars.
6 Central Jersey Tax + cost Casual dining loses volume.
7 Chicago, IL Crime perception, taxes Migration draining mid-market dining spend.
8 Boston, MA Cost + limited housing Strong tourism but locals moving out.
9 Hudson Valley, NY Rising prices Saturation in small-town dining.
10 Denver, CO Cost, congestion High competition, and nightlife plateauing.
11 Santa Barbara, CA High cost Smaller venues face labor pressure.
12 Seattle, WA Cost + policy fatigue Operators shifting to suburbs.
13 Stockton–Modesto, CA Spillover cost Limited nightlife growth.
14 Washington, DC Cost + remote work Lunch and after-work traffic decline.
15 Hartford, CT Stagnant wages Weak nightlife demand.
16 Tampa Bay, FL Overheating housing Volume-driven nightlife cooling.
17 Fresno, CA Low wage growth Margins get even tighter for restaurants.
18 Austin, TX Cost spike Boomtown-to-bust warning signs.
19 Bakersfield, CA Cost stresses Entry-level dining shrinking.
20 Philadelphia, PA Cost + crime narrative Suburban shift in nightlife spend.

The Story the Data Tells

1. The Southeast: America’s New Nightlife Frontier

Both Carolinas, Tennessee, Florida (particularly the northern region), and parts of Georgia are capturing massive lifestyle-driven migration.

Importantly, these states are luring more than retirees.

These markets reward:

  • approachable, high-vibe nightlife;

  • chef-driven but not overly precious dining;

  • hybrid concepts (sports lounges, social-gaming eatertainment, music-forward bars); and

  • suburban entertainment anchored in community.

I’m confident in saying that the southeastern US is where the next wave of innovative, experiential F&B will emerge.

2. High-Cost Coastal Metros: Bleeding Residents

It’s not like Chicago, Boston, Los Angeles, San Francisco, and Seattle are ghost towns. When it comes to hospitality, they’re destination cities with bars, restaurants, clubs, and hotels that are recognized on national and global stages routinely.

But the magnetic, tourist-attracting, accolade-winning concepts tend to be in the premium tier. Those concepts are winning (at least on the surface), but the middle in these destination cities is thinning out.

Mid-tier concepts in outflow cities are feeling the exodus. Operators firmly in the $25–$55 check average zone are exposed.

Meanwhile, comparatively, their high-end and budget peers are seeing healthier traffic and revenue.

3. Talent Migration: Reshaping Labor Markets

This may come as a shock but…hospitality professionals are also among those migrating in the US.

Chefs, bartenders, servers, bar backs, managers and other leaders… A not-insignificant number of our hospitality peers are also moving inland and south. They’re applying for roles when they arrive in inflow cities, changing up the labor pool.

Looking at outflow cities, the employment landscape in formerly top-tier markets becomes more competitive, and can become more expensive.

This is to say nothing of what migration does to demand. Emerging markets can suddenly support more concepts, particularly those that are innovative.

Some people who leave major markets may do so for a change in lifestyle. However, many still want access to a wide variety of restaurants, bars, and clubs. In some cases, they make investments in F&B concepts, reshaping the hospitality landscape of inflow cities.

On the other hand, hospitality groups see where populations are spiking, study those cities and the surrounding areas, and make their moves. Some will see an opportunity to move into a “new” market early, establishing themselves there before their competitors. Others will remain in a market in which they enjoy a strong position, planning to strengthen it even further as others leave.

4. The Mid-Sized City: Now the Sweet Spot?

Are you laser-focused on meeting guests where they are?

If you really believe in your concept, would you move to make it happen?

Would you strategize around an emerging market if a feasibility supported its viability?

Markets like Greenville, Chattanooga, Raleigh, and Huntsville are offering:

  • lower operating costs;

  • strong transplant populations; and

  • rapidly evolving taste profiles.

I think it’s safe to refer to some of these markets as the “next” Austins. They’re hot, but not so hot (yet) that they come with bloated startup costs.

Emerging markets can often offer very attractive startup positioning. This comes not only in the form of lower startup capital needs but also in the ability to stand out from already established offerings.

Key Takeaways for Operators

  • Consider following affordability trends rather than hype cycles.

  • Act early in mid-sized southeast and inland markets before saturation hits.

  • Expect tighter margins and slower traffic in coastal outflow markets, and in cities traditionally seen as premium, top-tier destination markets.

  • Anchor new concepts to emotional safety, community, and consistency. Each of those factors is contributing, at least in part, to today’s migration decisions.

  • Data > Vibes. Predicting the next market requires data—intelligence, facts, evidence—not vibes. There’s a reason KRG Hospitality starts with a feasibility study and follows it up with six other playbooks before completing the business plan, the final playbook in a set of eight.

Main source: PODS 2025 Moving Trends Report

Image: Microsoft Designer

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Where Canadians are Moving

Where Canadians are Moving

by David Klemt

An AI-generated image of a highly modified tuner car turned into a moving truck, with a long trailer adorned with Canadian maple leaves.

I don’t think anyone understands how much I need this “moving truck” to be real, and how much I want to drive it.

Data relating to inflow and outflow throughout Canada point to implications for major metros, mid-size markets, and hospitality.

On one side of the coin, there appears to be affordability-driven migration (mainly to Alberta). Flip that coin over and we see lifestyle-oriented shifts into smaller Ontario and BC markets.

U-Haul’s 2024 Growth Index gives us the cleanest nationwide list of the top inflow cities across Canada. For outbound trends, I’m analyzing StatsCan’s inter-provincial migration data, which shows where Canadians are exiting.

Most notably, Montréal, Toronto, and Vancouver appear to be experiencing the greatest outflow. And when people move, hospitality follows.

The hospitality implications of significant migration are enormous. Talent pools shift, concept viability changes, new nightlife pockets emerge, and major metros face softened demand outside tourist cores.

Before I get any further, a word of caution: As I’ve said countless times in articles, on podcasts, and in conversations, don’t move to a new-to-you (and your brand) market without data supporting that decision. (Scaling within a market in which you already operate also requires data.)

Below, the top inflow and outflow cities across Canada. Both charts also include possible opportunities and impacts.

Top 20 Canadian Inflow Cities (Operator-Focused Table)

Rank Market Key Drivers Hospitality & Nightlife Opportunities
1 Calgary, AB Affordability, jobs Massive opportunity for mid- to high-energy nightlife, and modern dining.
2 Edmonton, AB Jobs, cost Strong demand for new concepts; large population of younger guests and workers.
3 Belleville, ON Affordability Community-focused dining, pubs, and breweries.
4 Trenton, ON Military, cost Family dining and approachable bars.
5 Pembroke, ON Affordability Neighborhood restaurants, and pubs.
6 Brantford, ON Growth corridor Casual dining, lounges, and modern pubs.
7 Medicine Hat, AB Affordability Simple, approachable concepts.
8 Collingwood, ON Lifestyle, tourism High-end dining, wine bars, and boutique nightlife.
9 Parry Sound, ON Outdoor lifestyle Seasonal F&B and experiential venues.
10 Chatham–Kent, ON Affordability Family and value-driven dining.
11 Innisfil, ON GTA spillover Suburban nightlife.
12 St. Thomas, ON Industrial growth Mid-market restaurants.
13 Barrie, ON Boom-town status Strong bar and nightlife demand.
14 Woodstock, ON Growth hub Casual dining and social eateries.
15 Lindsay, ON Cost-driven migration Local-first hospitality.
16 Chilliwack, BC Less expensive than Vancouver Breweries and modern-casual concepts.
17 Owen Sound–Meaford, ON Lifestyle Seasonal and local-driven experiences.
18 Peterborough, ON Education and affordability Bars and casual dining.
19 Sydney, NS Cost, lifestyle Pubs and maritime-inspired dining.
20 Sidney, BC Vancouver Island draw Café culture and upscale casual concepts.

Top 15 Canadian Outbound Cities (Operator-Focused Table)

Rank Market (CMA) Key Push Factors Hospitality & Nightlife Challenges
1 Toronto, ON Housing cost, density Outflow of both talent and spend; mid-tier F&B softens.
2 Montréal, QC Wages vs. cost of living Growth slowing; nightlife remains strong but barbell-shaped.
3 Vancouver, BC Extreme housing cost Smaller venues under pressure; locals priced out.
4 Ottawa–Gatineau Cost and limited housing Restaurant scene stabilizing, slower growth.
5 Hamilton, ON Spillover cost Casual restaurants feel the squeeze.
6 Mississauga/Brampton Rising costs Suburban nightlife flattening.
7 Winnipeg, MB Slow wage growth Low spend-per-guest challenges.
8 London, ON Cost pressures Hospitality demand shifting outside city core.
9 Québec City, QC Aging population Limited nightlife expansion.
10 Kitchener–Waterloo Tech slowdown Bars and casual dining face softer demand.
11 Halifax, NS Post-COVID cost spike Tight labor, and slower local traffic.
12 Laval, QC Cost, suburban stagnation Dining segmentation increases.
13 Surrey, BC Cost pressures Strong immigration, but inter-provincial losses.
14 Burnaby, BC Housing strain Small-format restaurant pressure.
15 Richmond, BC Cost and saturation High competition, and tough margins.

The Story the Data Tells

1. New Growth Engine: Alberta

Calgary and Edmonton are growing. And with that growth both cities are also redefining Canadian hospitality demand.

Younger populations, strong wages, and realistic housing costs mean:

  • nightlife is expanding;

  • new F&B concepts can find traction quickly; and

  • talent is more readily available than in major coastal cities.

This signals, at least to me, that Alberta is on track to become Canada’s hospitality growth engine.

2. Booming: Smaller Ontario Cities

From Collingwood to Barrie to Belleville, these markets reward:

  • neighborhood-first hospitality;

  • experiential dining at accessible price points; and

  • venues with strong community roots.

Quality-of-life migration is strengthening the hospitality scene outside of larger markets.

It’s important for operators from major markets looking at such areas to keep in mind that they can’t simply swan in and expect success. They need data to support their move, and they need to prove themselves as supportive, beneficial members of the community.

3. Major Metros: Tourism Takes the Lead

Let me be clear: Montréal, Toronto, and Vancouver aren’t failing cities. They’re not about to look like locations in an I Am Legend sequel or reboot.

However, Canada’s major markets are no longer “automatic wins” for operators. That is to say, metros that were once no-brainer target markets for starting or scaling must be approached with more caution.

It’s quite likely that the secondary markets surrounding major metros are now the superior choice in many instances for restaurants and bars just starting out. They’re also likely the more logical choice for brands looking to expand (particularly those operating in major metros already).

That said, primary locations like Montréal, Toronto, and Vancouver can (and should) leverage tourist traffic. Tourism is crucial to their downtowns, as is the case for essentially every destination city.

Tourists will become even more valuable to operators in major metros as locals continue to exit to more affordable, smaller cities.

However, this also highlights the importance of operators pulling every operational and guest experience thread tighter.

Support from locals remains paramount. Locals spend their money where their needs are met. They reward operators and teams for excellence, their coolness factor, goodness, and consistency.

Increasing the focus on tourists is wise; decreasing focus on locals would be foolish.

4. Risky Business: Labor and Cost Stacking

Operators are fighting:

  • high rents;

  • labor shortages; and

  • declining local spending.

This is the combination that closes otherwise good venues.

Operators experiencing this cost stack must pursue strategic clarity, and be more intentional with every detail.

Each element of the guest experience needs review, from discovery and stepping through the doors for the first time, to the exit and follow-up. Entertain your guests like you mean it, because you do mean it.

Actual processes for hiring, onboarding, and ongoing training must be carefully considered, implemented, and non-negotiable.

Costs must be controlled, not simply cut. Discounting isn’t strategic, it’s reactive.

Key Takeaways for Canadian Operators

  • Alberta and mid-sized Ontario markets look to be the near-term winners.

  • Large metros require precise, high-margin, experience-forward concepts. Generic offerings are going to close doors.

  • Lifestyle locales are emerging hot spots for elevated, boutique hospitality.

  • Follow the talent. Staff movement is often the earliest signal of a market shift.

Before making any move into a new market, remember that data is superior to vibes. Conduct a feasibility study, create a concept plan and the other playbooks you need to make an informed decision, and then craft your business plan. Your business plan does not come first; it’s informed by the seven playbooks that precede it.

Main sources: U-Haul 2024 Growth Index (Canada) and StatsCan inter-provincial migration deficits (2023–24)

Image: Microsoft Designer

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Ditch Draconian Drink Development

Ditch Draconian Drink Development

by David Klemt

Hand throwing two red dice on a dark gaming table

This is not a viable business strategy.

As we enter the holiday season we need to reiterate that a single person can influence the bar and restaurant decision for an entire group.

Let me be even more blunt, now that I’ve got you here. As we head into 2026, I find it a bit shocking that we still need to address alcohol-free programming.

A recent trip to Colorado is putting this topic back in the spotlight for me. Pair it with menu programming for clients and I simply can’t let it go.

KRG Hospitality was in Denver for The Hospitality Show and Bar & Restaurant Expo 2025. President and principal consultant Doug Radkey spoke on a panel with chef and restaurateur Adrianne Calvo and chief marketing officer Lauren Barash.

While we were in town for the show, we attended other education sessions. One of these was “Trend on Tap,” which focused on beverage trends.

The entire panel was insightful, but something said by Miranda Breedlove, the national director of bars for the Lifestyle Division of Hyatt Hotels, really stood out to me.

To summarize, a single person—the non-drinker—has the power to decide which bar or restaurant a group chooses to visit.

Who, not Why

Let’s be clear about a crucial point: It doesn’t matter why someone has chosen to not consume alcohol.

A person may never drink alcohol. They may choose to forego alcohol for a month, week, or day. Someone may decide to stop consuming alcohol during a visit to a bar or restaurant.

None of that matters. What’s important is being respectful of that decision, being hospitable regardless.

One effective way of showing respect for that choice is giving more than a few seconds consideration to your zero-proof options.

In this situation, the who is more important than the why.

Who is the guest your zero-proof program is trying to reach? The guest who decides they want a zero-proof drink.

Why don’t they want to drink alcohol? It doesn’t matter. Why doesn’t it matter? It’s nobody’s business.

The only “why” relevant to this situation is, why are you taking the time to consider a well-crafted, zero-proof program? To be hospitable and serve all of your guests to the best of your ability. That’s good business in the hospitality business.

Which Sounds Better?

I’m going to present you with two options to consider.

Which sounds like a more enjoyable experience to you:

Option 1: Guests who want a non-alcohol drink are limited to water, soda, or juice in a bottle or can, or off the gun.

Option 2: Guests find a curated, zero-proof section on your menu, and experience the same service and presentation as guests who order low- or full-proof cocktails.

Of those two options, which seems like it delivers a memorable guest experience? Which option ensures a guest who doesn’t want to consume alcohol feels comfortable and valued?

I know I wouldn’t bother returning to a bar or restaurant that made me feel alienated rather than welcomed. And if I’m in a group of people, as Breedlove said, I can influence them to avoid that venue while we’re discussing where to go.

Rolling the Dice

Failing to develop an intentional, well-curated non-alc program is rolling the dice.

You’re rolling the dice on the guest experience. Rolling the dice on transforming first-time visitors into repeat guests.

And, in 2025, nearing 2026, you’re rolling the dice on your brand’s perception.

Sure, ten years ago or so the viability of zero-proof was debatable. Some operators and bartenders saw the value in appealing to guests, whether sober or sober in the moment, and treating them to the same experience as every other guest.

In the other camp, operators and bartenders who saw non-alc cocktails as a waste of time. I remember hearing bartenders say that making zero-proof drinks was pointless because they didn’t make the bar money, and didn’t make them tips.

However, it’s no longer debatable; refusing to be intentional about a zero-proof program for your bar or restaurant is bad business.

The proof is in the decision-making process. If the non-alcohol drinker can make the final choice for bar or restaurant selection for an entire party, it proves the importance of non-alc.

Not Done Yet

Breedlove made another excellent point that also relates to outdated thinking about beverage programs.

To paraphrase Breedlove, “batching” is not a bad word.

This is particularly true for high-volume bars. Likewise, it’s true of high-demand signature drinks that drive sales for a particular bar or restaurant.

As Breedlove said, if the drink won’t suffer, put your high-volume orders on draft. The reasoning is simple: your team likely can’t put out as many of a high-performing, high-volume drink to order as they can if it’s batched.

More of that popular, revenue-driving order going across the bar means more revenue, more tips, and reduced ticket times. Overall, it’s a win-win: better for the bottom line, and better for the guest experience.

And, as I’m sure you’ve put together, this can apply to your zero-proof menu. Have a killer non-alc Margarita? Put it on draft, save time in service.

The key to success, whether batching alcohol or non-alcohol drinks, is in the presentation. Give careful consideration to your ice program, glassware, garnish, and presentation so guests don’t feel shafted regarding the experience.

We’re having to adapt in hospitality once again. We need to make sure we’re moving past outmoded ways of thinking so we can move forward quickly and with strategic clarity.

Image: Leon-Pascal Jc on Unsplash

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Excellence Fuels Influence in Hospitality

Excellence Fuels Influence in Hospitality

by David Klemt

The word "excellent" in a vintage script, superimposed over the image of a pint on a bar top.

Cool grabs attention. Good builds trust. And excellence? Excellence transforms your brand into an industry benchmark others want to emulate.

When someone recognizes a hospitality brand’s excellence, when they admire it, that means they respect how its team operates. They see consistency, character, leadership, and the brand’s aesthetic.

They see something that resonates with them. Something they’d recommend, talk about, maybe even want to copy to some degree. When a brand’s excellence is grounded in authenticity rather than performance, it becomes a serious competitive advantage.

The Five Traits of Excellence

When I first looked into these traits, they were described as “admirable,” or the characteristics associated with “admirability.”

However, I’ve had time to sit with these traits, and I feel it’s more appropriate to view them through the lens of excellence.

With that out of the way, research reveals five recurring traits of excellence (or admirability, if you prefer):

  • Attractive
  • Competent
  • Desirable
  • Friendly
  • Trendy

These traits represent perceived value. Not just operational performance, either. They’re tied to the vibe, confidence, and cultural relevance that set brands operating at a higher level—excellence—apart from the rest.

Attractive: First Impressions Still Matter

Let’s not pretend aesthetics don’t matter.

Attractive brands look the part. They photograph well. They feel polished. However, the polish goes deeper than surface level. The aesthetic is part of a greater brand alignment.

Branding communicates and supports identity. Design supports the experience. Everything feels intentional.

You don’t need marble countertops or $300,000 lighting installs to succeed. Yes, those can be fantastic details, but they don’t automatically lead to excellence.

What’s necessary is cohesion, confidence, and strategic clarity in how your brand shows up every day.

Look like you believe in your concept. Most importantly, just don’t look it, live it.

Competent: Show Your Mastery Without Flash

Competence is often invisible when it’s done right. On the flip side, it’s painfully obvious when it’s missing.

Competent brands:

  • run tight ops;
  • deliver consistent product and/or service;
  • empower their teams to handle problems before they escalate; and
  • communicate clearly, inside and out.

Guests and staff trust competent brands because they follow through.

It’s not about perfection. As Bruce Lee is quoted as saying, “If you are cursed with perfectionism, then you’re absolutely sunk. This ideal is a yardstick which always gives you the opportunity to browbeat yourself.”

Instead, it’s all about professionalism and developing leadership skills.

Desirable: Create Pull Without the Performance

Desirability isn’t just about being booked out or trending. I’m not saying those are problems; both are excellent goals to pursue.

What I’m saying is an even better goal is to become someone’s desired brand. You want to lead your business to the level of excellence that makes it the first that comes to mind when someone wants to feel seen, celebrated, cool, or impressed.

People want to be associated with desirable brands. This absolutely applies to hospitality businesses. Guests want to be wowed and motivated to post about your business. They want to host their friends at your spot. They want to bring dates to you and your team, to visit with their colleagues and clients after meetings.

But you have to blow them away with excellence and make your brand desirable.

Desirability shows up when your space aligns with identity. It’s when people say, “This feels like me,” or, “I fit in here.”

Friendly: Be Approachable Without Losing Edge

Hospitality can’t be excellent if it’s cold. Friendliness is the bridge between capability and connection.

In admired brands, friendliness isn’t a script, it’s embedded.

It’s how the hosts greet guests. How managers lead the floor, and how bar teams communicate under pressure. Friendliness, like excellence itself, is achieved by nailing every step and every detail.

Your team is a reflection of your brand’s personality, and leadership’s reinforcement of standards surrounding tone and attitude. Regardless of personality, friendliness needs to be a pillar of your brand; it’s a cornerstone of hospitality.

That doesn’t mean dulling your edge if you, your team, and your brand have one. In that case, it means balancing edginess with professionalism and being warm and welcoming.

So, make sure friendliness isn’t something you or your team fake. Just like believing in your own brand, your team needs to actually live hospitality.

Trendy: Be Culturally Aware, Not Chameleonic

Trendiness is tricky.

Do it well and you feel current. You and your team are plugged in, exciting.

Do it wrong? You feel desperate.

Excellent, admirable brands don’t chase trends, they curate them. Excellent brands set the pace rather than follow someone else’s.

These are the brands that understand what fits their DNA, and, perhaps more importantly, what doesn’t.

Think of trendiness as a signal that you’re paying attention and evolving but not forgetting who you are and losing your brand identity.

Excellence Attracts Talent, and Keeps It

It’s no secret this industry has a labor challenge. But what’s often missed is that excellence works like gravity on guests and on talent.

People want to work somewhere led by someone that gives them a sense of pride. They want to work somewhere that gets talked about for the best reasons. They’re eager to be part of a brand that provides them near-daily opportunities to say, “I helped build this.”

So, give that to them. Become the leader in your market with the team that others are eager to join.

When your brand is admired, recruiting becomes less about chasing candidates and more about filtering them. You attract people aligned with your mission, energy, and culture.

Even better? Admiration born of excellence drives retention; people stay where they feel proud, seen, empowered, and challenged.

Excellence Inspires the Next Generation

When you lead your brand to excellence, you’re not just running a business, you’re helping shape the future of hospitality.

Operators who work toward, achieve, and maintain excellence become case studies. They get quoted, referenced, and emulated.

And whether they know it or not, they spark ambition in others. They inspire the bartender who dreams of opening their own cocktail bar. The server who’s sketching out a fast-casual concept. They’re a mentor to the GM who eventually moves on in their hospitality journey and launches their own successful concept.

Excellent leaders turn staff into students, and transform students into operators, and the cycle continues.

That’s a legacy. That’s leadership. It’s one of the most underrated impacts of getting all of this right.

Why Excellence Drives Long-Term Value

Cool is magnetic. Good is reliable. Excellence is memorable.

Excellent brands get the press, the partnerships, and the loyalty that goes beyond convenience.

They attract talent that wants to grow with them, not just collect a paycheck.

Admired brands:

  • operate with integrity;
  • evolve with purpose;
  • communicate with confidence; and
  • stay consistent in chaos.

To that last point, an excellent brand’s standards are so concrete, so non-negotiable, that they’re capable of thriving in chaotic situation. In fact, they defeat chaos and learn from it.

In short, excellence leads whether it’s trying to or not.

Reflection Questions for Operators

  1. What’s one thing your brand does that genuinely earns admiration rather than just attention?
  2. Are your aesthetics aligned with your service culture?
  3. Do your team members feel proud to represent your concept?
  4. What trends have you adopted that actually fit your identity?

The Final Bite: Know Who You Are, Then Amplify It

Now that you’ve seen all three dimensions —coolness, goodness, and excellence—you’ve got a strategic lens most operators never even consider.

It may seem overwhelming to consider 19 traits and how they relate to your brand. Luckily, you don’t need to master all of them. What you need to do is lead with intention.

Know who you are, amplify that, and remember:

  • Cool gets them in.
  • Good keeps them in.
  • Excellence makes them talk.

Want to build a brand that lasts? Get intentional about how people perceive you, and how your team lives that perception every single shift.

Image: Canva

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Good: Trust & Comfort Build Loyalty

Good: Trust & Comfort Build Loyalty

by David Klemt

The word "good" in a vintage script, superimposed over the image of a pint on a bar top.

Cool grabs attention because it’s magnetic and buzzworthy. But if you want people to come back and bring others with them, cool isn’t enough.

You need to be good.

However, when I say “good” I’m not talking about being nice, or offering competent service. This is hospitality; those are (or damn well should be) a given.

In hospitality, in this context, good is about emotional safety, reliability, and the kind of consistency that turns a first-time guest into a regular.

The best hospitality brands do more than just impress, they reassure.

The Eight Traits of Good

According to cross-cultural psychology research, eight traits consistently define what people perceive as “good” in others. We can apply these traits to brands as well.

I shared them earlier this year:

  • Agreeable
  • Calm
  • Conforming
  • Conscientious
  • Secure
  • Traditional
  • Universalistic
  • Warm

If cool is what gets guests in the door, good is what makes them feel welcome, seen, and safe enough to stick around.

Agreeable: Cooperative and Empathetic

Just as you can pick up on tension within moments of stepping inside a given venue, you can feel it when a venue is easygoing.

The team’s on the same page. The energy is collaborative. There’s a sense of mutual respect between staff and guests, and between team members and leadership.

Notably, however, being agreeable in hospitality isn’t about people-pleasing. In reality, it’s about creating a culture of empathy and professionalism.

When you step into such a venue you notice that hospitality isn’t forced, it’s practiced.

Calm: Clear-Headed Under Pressure

Calm hospitality environments feel better. They’re emotionally steady.

The pace may be fast, but the energy is measured, controlled, and confident. Guests pick up on this instantly, and so do team members.

When your culture is calm, you and your team don’t just survive a busy night, you all come together, thrive, and make it look easy.

Conforming: Reliable and Predictable (In the Best Way)

Let’s redefine “conforming.” When I use it in this context, I’m not talking about suppressing creativity. Instead, conformity is an alignment with expectations.

Guests return when they know what to expect. They come back when they trust that the experience will meet the impeccable standard you and your team have set every time.

It’s the culmination of onboarding, continuous training, non-negotiable SOPs, structure, and consistency.

Conformity, in this way, isn’t boring, it’s dependable.

Conscientious: Detailed and Purpose-Driven

Conscientious brands care about the little things. They’re organized, thoughtful, and consistent, and that shows up every shift in a multitude of ways.

It’s how the bar team garnishes each drink. How clean the bathrooms are kept. How team members communicate with each other, leadership, and guests throughout their shifts.

It comes through in your consideration of each and every touch point that guides the guest journey.

Conscientiousness builds trust. You’re delivering on the promise to your guests and your team that you don’t cut corners.

Secure: Safe, Seen, and Stable

Safety in hospitality isn’t just physical, it’s emotional.

Guests want to know that you’re going to take care of them because you respect them. You respect their decision to visit your venue, spend their time with you and your team, and spend their money inside your business.

Likewise, your team members want to feel protected, heard, supported, and empowered. To provide an example, I’ve made it clear more than once in articles and on the Bar Hacks podcast that I expect leadership to support team members. No, the guest isn’t always right. “The customer is always right” isn’t just an abused misquote, it’s an outdated sentiment any way you slice it.

I expect leaders to step in and handle all guest complaints; that’s a crucial part of the job. Do you want your team to believe in your concept? They had better be given proof that they should believe in leadership.

Security is built through:

  • clear boundaries;
  • steady leadership;
  • well-trained staff;
  • staff that feels cared for and respected; and
  • real accountability, regardless of role.

If your guests feel nervous or confused—and they will if that’s how your team feels—you’ve lost them.

Traditional: Grounded, Not Outdated

Tradition gets a bad rap in modern branding. Traditional values—community, respect, attention to ritual—are deeply comforting.

When used well, tradition creates familiarity and nostalgia, particularly at neighborhood spots, legacy venues, or family-forward brands.

And even modern, forward-thinking spots can lean on traditional service values without feeling dated.

Universalistic: Fair, Equal, and Consistent

This is where your hospitality values shine.

Universalistic brands don’t treat some guests better than others. They don’t ignore or dismiss certain demographics.

A universalistic hospitality brand operates from a belief that everyone deserves a great experience.

That belief, that value, creates equity. Equity creates trust.

Once you’ve earned that trust, you need to commit to keeping it. As the saying goes, “Trust takes years to build, seconds to break, and forever to repair.”

Warm: Friendly, Kind, and Human

Warmth is the final, and arguably most important, “good” trait.

Warmth shows up in tone, body language, follow-through, and how guests are made to feel the moment they walk in.

Anyone can serve someone. Warmth is what makes someone feel welcome.

Why “Good” Hospitality Brands Last

Good is often invisible. It doesn’t always get the hype but it builds return visits.

Goodness is what builds reputation, earns word-of-mouth referrals, and retains guests and team members.

Good brands become a reliable part of someone’s routine. They’re the go-to when friends visit from out of town. The default when someone asks, “Where should we go tonight?” They’re the first venue that pops into someone’s head when they think “date night.”

Reflection Questions for Operators

  1. Where does your team already show strength in “good” traits?
  2. Which of these eight traits does your guest journey express naturally?
  3. Which ones feel like gaps, and how could they be reinforced operationally?
  4. Are your brand values visible in your culture and your service, or are they just words on a website and inside an employee manual?

Up Next: Quantifying Excellence

In the final part of this series, we’ll unpack what it means to be seen as excellent, and how that perception drives brand equity, team pride, and long-term influence.

Because once you’ve nailed cool and good, excellence is what turns your brand into a benchmark.

Image: Canva

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Cool: Magnetism Matters in Hospitality

Cool: Magnetism Matters in Hospitality

by David Klemt

The word "cool" in a vintage script, superimposed over the image of a pint on a bar top.

We all know what it feels like to walk into a cool space. The room hums, the lighting hits just right. The music, the people, the energy…it’s magnetic.

But when we talk about cool in hospitality, too often we’re referring to aesthetic alone: the vibe, the lighting, and the playlist, among other details.

The truth? Cool isn’t just visual. And it’s not trend-chasing.

Cool is a collection of behavioral traits. When those traits are intentional, the perception of cool becomes strategic. In turn, that magnetism becomes a strategic element.

The Six Traits of Cool

Cool can feel elusive, but it’s not mystical.

Cross-cultural research has identified six traits that people consistently associate with coolness.

They are:

  • Extraverted
  • Hedonistic
  • Powerful
  • Adventurous
  • Open
  • Autonomous

Let’s break them down, and apply them to hospitality.

Extraverted: Show Up and Stand Out

Cool brands don’t hide in the background.

They communicate clearly, loudly, and often. They show up on social and in the community. Cool brands own their tone.

However, they’re not loud for the sake of making noise. It means that they own the room without apology.

Think confident service teams, guest-forward experiences, and spaces designed for connection rather than just consumption.

Hedonistic: Make People Feel Good

Let’s kill the negative spin on the word “hedonistic” right from Jump Street.

In this context, it simply means “pleasure-oriented.”

Cool brands create experiences that feel good. Not just pleasant, memorable.

Drinks that hit flavor and presentation. Lighting that makes everyone look and feel attractive. Flow that feels frictionless.

This is about sensory impact. It’s why people will choose your place even if another spot has better prices or faster service.

Guests aren’t really buying food or drink; they can make either at home. They’re buying the feeling you, your team, and your venue gives them. In reality, they’re buying your cool, expecting it to reflect onto them.

Powerful: Influence, Not Ego

Power in a hospitality setting doesn’t mean dominating the scene.

For a hospitality brand, power means having influence. That influence makes guests feel like they’re somewhere that matters.

Power shows up when:

  • your venue sets trends instead of following them;
  • your team leads with confidence and autonomy; and
  • people talk about your space and brand when you’re not in the room.

A powerful brand doesn’t have to scream, it simply can’t be ignored.

Take the phrase, “real wealth doesn’t scream, it whispers.” Now, replace “wealth” with “coolness.” Do you believe someone when they loudly tell you that they’re cool? Or do you sense when they communicate it without having to say a word?

Adventurous: Show Some Edge

Cool brands take risks.

Try new menu items, new event formats, new collaborations. Don’t wait for permission, just do it.

However, keep in mind that risk and adventure don’t necessarily require recklessness. They simply require you to indicate, with confidence, that you’re willing to experiment publicly.

This could look like a pop-up collab with a neighboring venue. Hosting an event, a person, or a brand that’s never been seen or experienced in your market. Reinventing a tired night of the week with a totally new promotion.

Predictability is comforting, but adventure creates buzz. Be the buzz.

Open: Let the Culture In

Being open means staying curious to new ideas, influences, voices, and formats.

Guests notice when a brand is receptive, diverse, and dynamic. They reward that with their loyalty.

Openness in hospitality looks like:

  • Welcoming feedback, and acting on it.
  • Hiring for perspective rather than just experience.
  • Rotating menus or programming to reflect seasonality and community.

Cool doesn’t look the same in every city or concept. Openness helps you localize your identity without diluting your brand.

Autonomous: Lead with Vision, Not Imitation

The coolest brands feel like they were born fully formed,  even if we know the reality is messier and took years to perfect.

Why? Because they make decisions as themselves, not in response to what others are doing.

Autonomy shows up when your voice and values are clear across every touch point. When you stay consistent, even when competitors pivot. Your autonomy comes through when finally figure out what you’re not trying to be.

Hospitality is full of sameness. Cool stands out when it’s driven by clarity.

Why Cool Still Matters

Cool isn’t shallow, and it isn’t fleeting. Not when it’s rooted in these six traits.

Cool matters because it creates curiosity, conversation, and connection.

It’s what gets people to check you out, to take a risk and try you. That decision to try you is the first step to becoming a loyal guest, team member, or partner.

But remember that while cool can grab people’s attention and create energy, it’s not capable of creating sustainability on its own. You need systems in place to stabilize and scale.

A Few Reflection Questions

  1. What part of your guest experience feels truly cool right now?
  2. What parts feel tired, safe, or imitative?
  3. Which one of the six traits comes to your concept most naturally?
  4. Which one could you amplify intentionally this month?

Next Up: Quantifying “Good”

In the next installment, we’ll talk about the eight traits that make a brand feel good, the kind of hospitality that builds trust, reputation, and retention.

Until then, stay cool.

Image: Canva

Client Intake Form - KRG Hospitality

by David Klemt David Klemt No Comments

Talkhouse Encore Aims for Iconic

Talkhouse Encore Aims for Iconic

by David Klemt

Person holding a can of Talkhouse Encore against their blue sweater with a bear on it

That’s a rad sweater.

In a move that highlights the brand’s forward-thinking commitment to growth, Talkhouse Encore is appointing a Vice President of Marketing.

If you’re a regular reader you’re aware that I don’t share every bit of industry news. Hospitality moves quickly, and developments flow steadily. Appointments, case sales, market expansions… There’s a lot to monitor.

However, I do love to watch Bar Hacks podcast guests grow. It’s a privilege to check in with them and share where they are in their journeys with listeners and readers. On episode 141,  I speak with Talkhouse Encore’s president and co-founder Robert Minucci.

We dive into the story behind the premium RTD brand’s inception: its connection to an iconic music venue, putting in the work to grow in a highly competitive category during the pandemic, and facing skeptical (sometimes cynical) distributors.

Minucci shares how his business partner, Ruby Honerkamp, sought to bring the spirit of Stephen Talkhouse to the masses through “dive bar classic” vodka and tequila seltzers.

At the brand’s core: authenticity and flavor. In particular, there’s a focus on earning brand loyalty from legal-age Gen Z consumers. Speaking broadly, Gen Z wants a story and a connection to a brand. Really, it’s what most people want these days.

Connection Through Authenticity

During our conversation, Minucci explains how the small-but-nimble team focuses on building a strong local presence before considering expansion, ensuring that they meet consumer demands with quality ingredients and an engaging brand narrative.

If, as the saying goes, you can’t do epic things with basic people, it stands to reason that you can’t build an iconic brand with a basic team. And when your brand has a direct connection to an icon—in this case, a revered live music venue—the pressure to reach similar status is very real.

This is where the newly-appointed Vice President of Marketing takes the stage to help tell the Talkhouse Encore story.

Boasting nearly a decade of experience building and growing brands, Courtney Roth is a clear signal to the market: Talkhouse Encore is here.

“At Talkhouse Encore, our mission is to be more than just another canned cocktail. We want to be the drink that brings people together for unforgettable moments,” says Roth. “I’m excited to lead marketing efforts that connect with consumers through authentic experiences, social storytelling, and grassroots programs that make Talkhouse Encore the go-to choice for today’s drinkers.”

Aiming for Iconic

Aiming for epic and iconic certainly seems to be a key driver of Roth’s brand storytelling. She developed her mastery of lifestyle brand marketing at Diageo. Pepsi benefited from her positioning prowess when she led their Super Bowl LVII activations.

Proving she knows how to build connections at the consumer level, Roth led the sampling of 1.5 million cans of Alani Nu. Earlier this year, Alani Nu was acquired for $1.8 billion by Celsius, which itself saw PepsiCo increase its stake in the energy drink brand juggernaut to 11 percent.

Those are just a few of Roth’s marketing and expansion accolades.

“I’m thrilled to step into the VP of Marketing role at Talkhouse Encore,” says Roth. “My focus is on building out an omni-channel marketing strategy that introduces more consumers to our premium vodka and tequila sodas. We’re setting the stage for significant growth in 2026 and beyond!”

This appointment is a signal that Talkhouse Encore intends to expand to an increasing number of markets over the course of the next 12 months. Keep your eyes peeled for activations and your opportunity to sample and engage with the brand.

To learn more about Talkhouse Encore, visit their website. Give them a follow an Instagram for news, activations, and more.

Disclaimer: Neither the author nor KRG Hospitality received compensation, monetary or otherwise, in exchange for this post.

Image provided by Talkhouse Encore

Client Intake Form - KRG Hospitality

Chat with Doug